Critical Minerals and Energy Intelligence

Copper, tungsten and antimony supply capacity to grow under 2% a year to 2030

  • world capacity to mine or produce six of the eight critical minerals in a new US Geological Survey outlook (antimony, copper, niobium, silicon metal, silver and tungsten) is set to grow by just 4% to 10% in total between 2025 and 2030, or under 1% to about 2% a year
  • copper mine capacity is projected to rise about 9% from nearly 30 million tonnes in 2025, compared with a 12% rise in world copper mine output over the previous five years, while BloombergNEF expects a copper deficit from 2028
  • China holds about 70% of 2025 capacity for natural graphite and tungsten and 87% for silicon metal, while Brazil holds 92% of niobium
  • only natural graphite and potash grow faster, by about 18% to 20%, but graphite mines used just 45% of their capacity in 2025 as Chinese producers ran at a loss to hold market share


World capacity to mine or produce six of eight critical minerals, including copper, tungsten and antimony, will grow by just 4% to 10% between 2025 and 2030, according to a new US Geological Survey (USGS) outlook.

That is the total over five years, or under 1% to about 2% a year. The six minerals include:

  • copper
  • tungsten
  • antimony
  • niobium
  • silicon metal
  • silver

Only natural graphite and potash are expected to grow faster, by about 18% to 20%.

The World Minerals Outlook covers eight minerals on the 2025 US critical minerals list, and the US depends on imports for more than half of its consumption of each one.

In contrast to the latest projections, world copper mine output rose about 12% in the five years to 2025, from 20.6 million tonnes in 2020 to an estimated 23 million tonnes, and silver output rose about 11%, from 23,500 tonnes to 26,000 tonnes. Output and capacity are different measures, but the USGS now expects capacity for the two metals to grow by only about 9% and 4%.
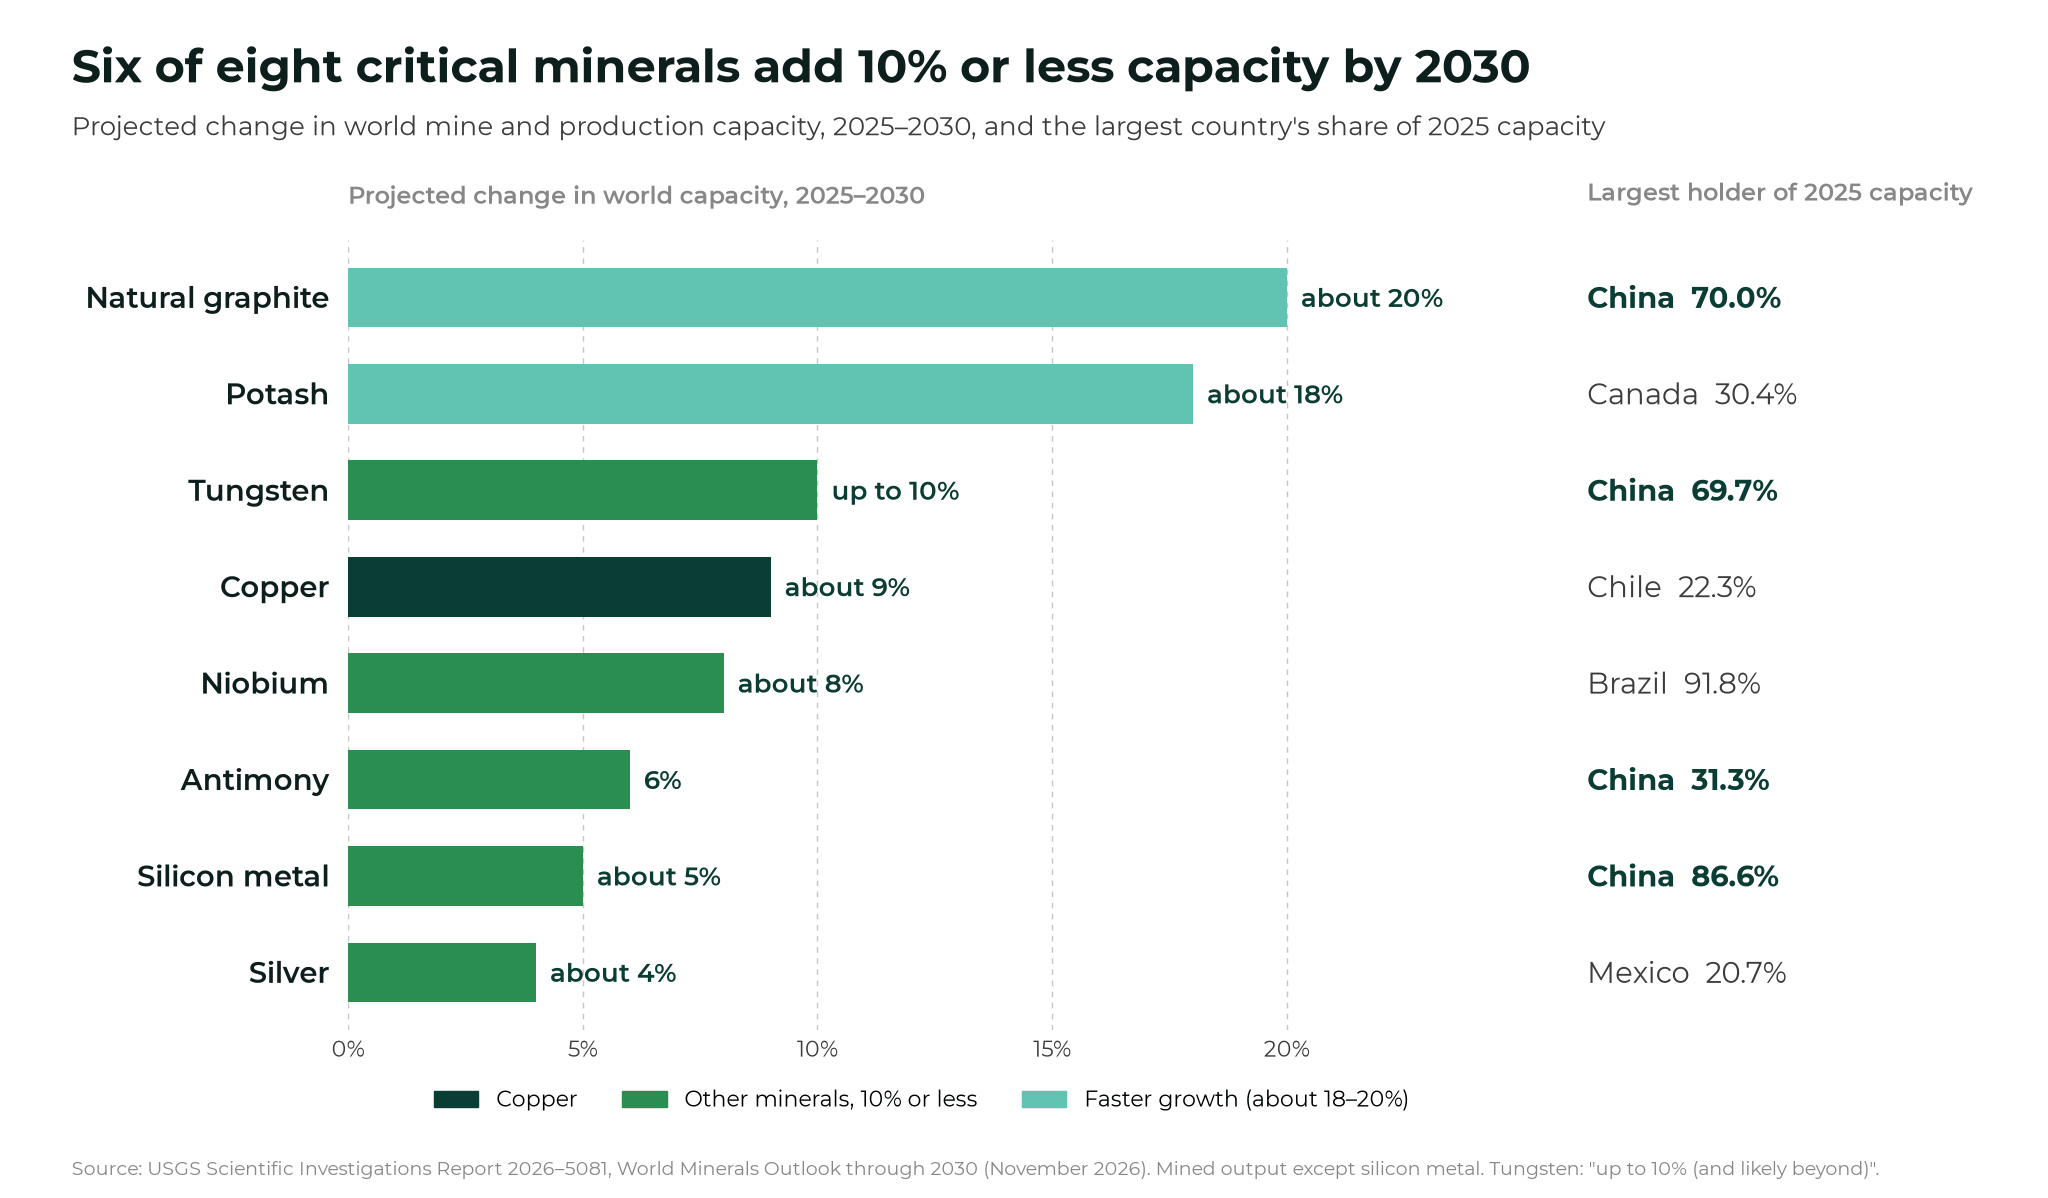
Bar chart of projected change in world mine and production capacity from 2025 to 2030 for eight critical minerals: natural graphite about 20%, potash about 18%, tungsten up to 10%, copper about 9%, niobium about 8%, antimony 6%, silicon metal about 5% and silver about 4%, with the largest country's share of 2025 capacity for each.

Copper adds less than 2% a year

Copper mine capacity was nearly 30 million tonnes in 2025, with Chile, the Democratic Republic of the Congo, Peru, China and the US holding 59% of it. It barely moved from 29.5 million tonnes in 2023 to 29.6 million tonnes in 2024 and is set to rise about 9% by 2030.
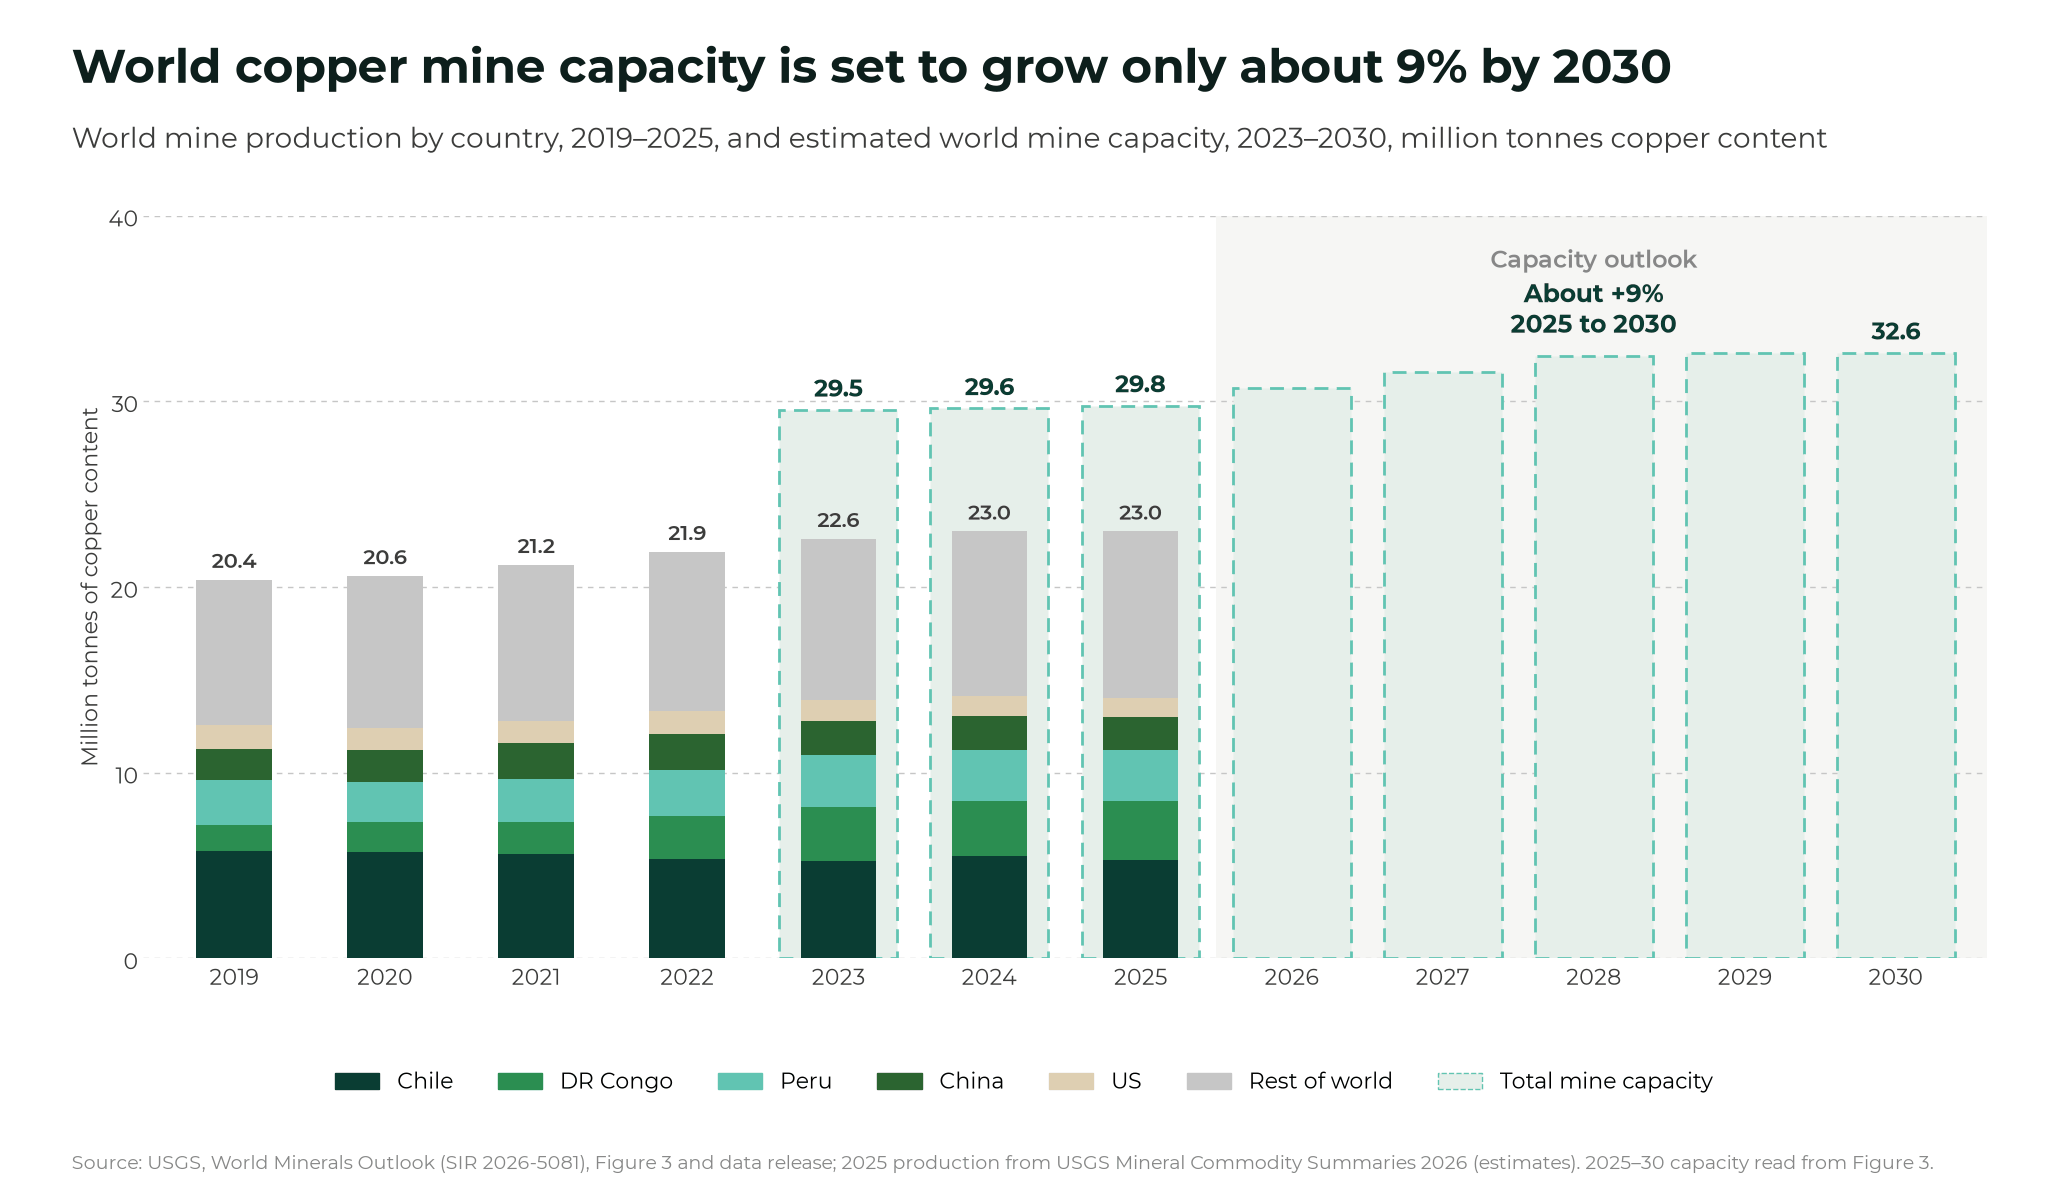
Stacked bar chart of world copper mine production by country 2019-2025 with estimated world mine capacity rising from 29.5 million tonnes in 2023 to about 32.6 million tonnes in 2030

The challenge is that demand is moving faster that projected supply.

BloombergNEF forecasts a copper deficit from 2028 and demand up 61% between 2026 and 2050, while the USGS points to falling ore grades, rising capital costs and long permitting timelines holding back new mines.

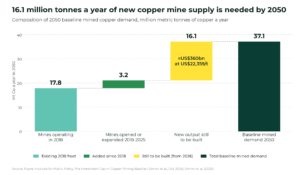
As we reported in our earlier article on the US$360 billion of new copper mines the world needs by 2050:

“new mines take an average of 17 years to come into operation, so the shortfall could persist for decades”

China holds the capacity for graphite, silicon and tungsten

Supply of the other minerals is also heavily concentrated, with China holding 70% of natural graphite capacity, 87% of silicon metal and 69% of tungsten, while Brazil holding 92% of niobium.

The example of tungsten shows what such concentration can means for prices: after China put new export controls on some tungsten products in February 2025, prices for tungsten concentrate and ammonium paratungstate, a key tungsten intermediate, more than doubled in 2025. Close to a dozen mine projects outside China plan to start in 2028 or later.
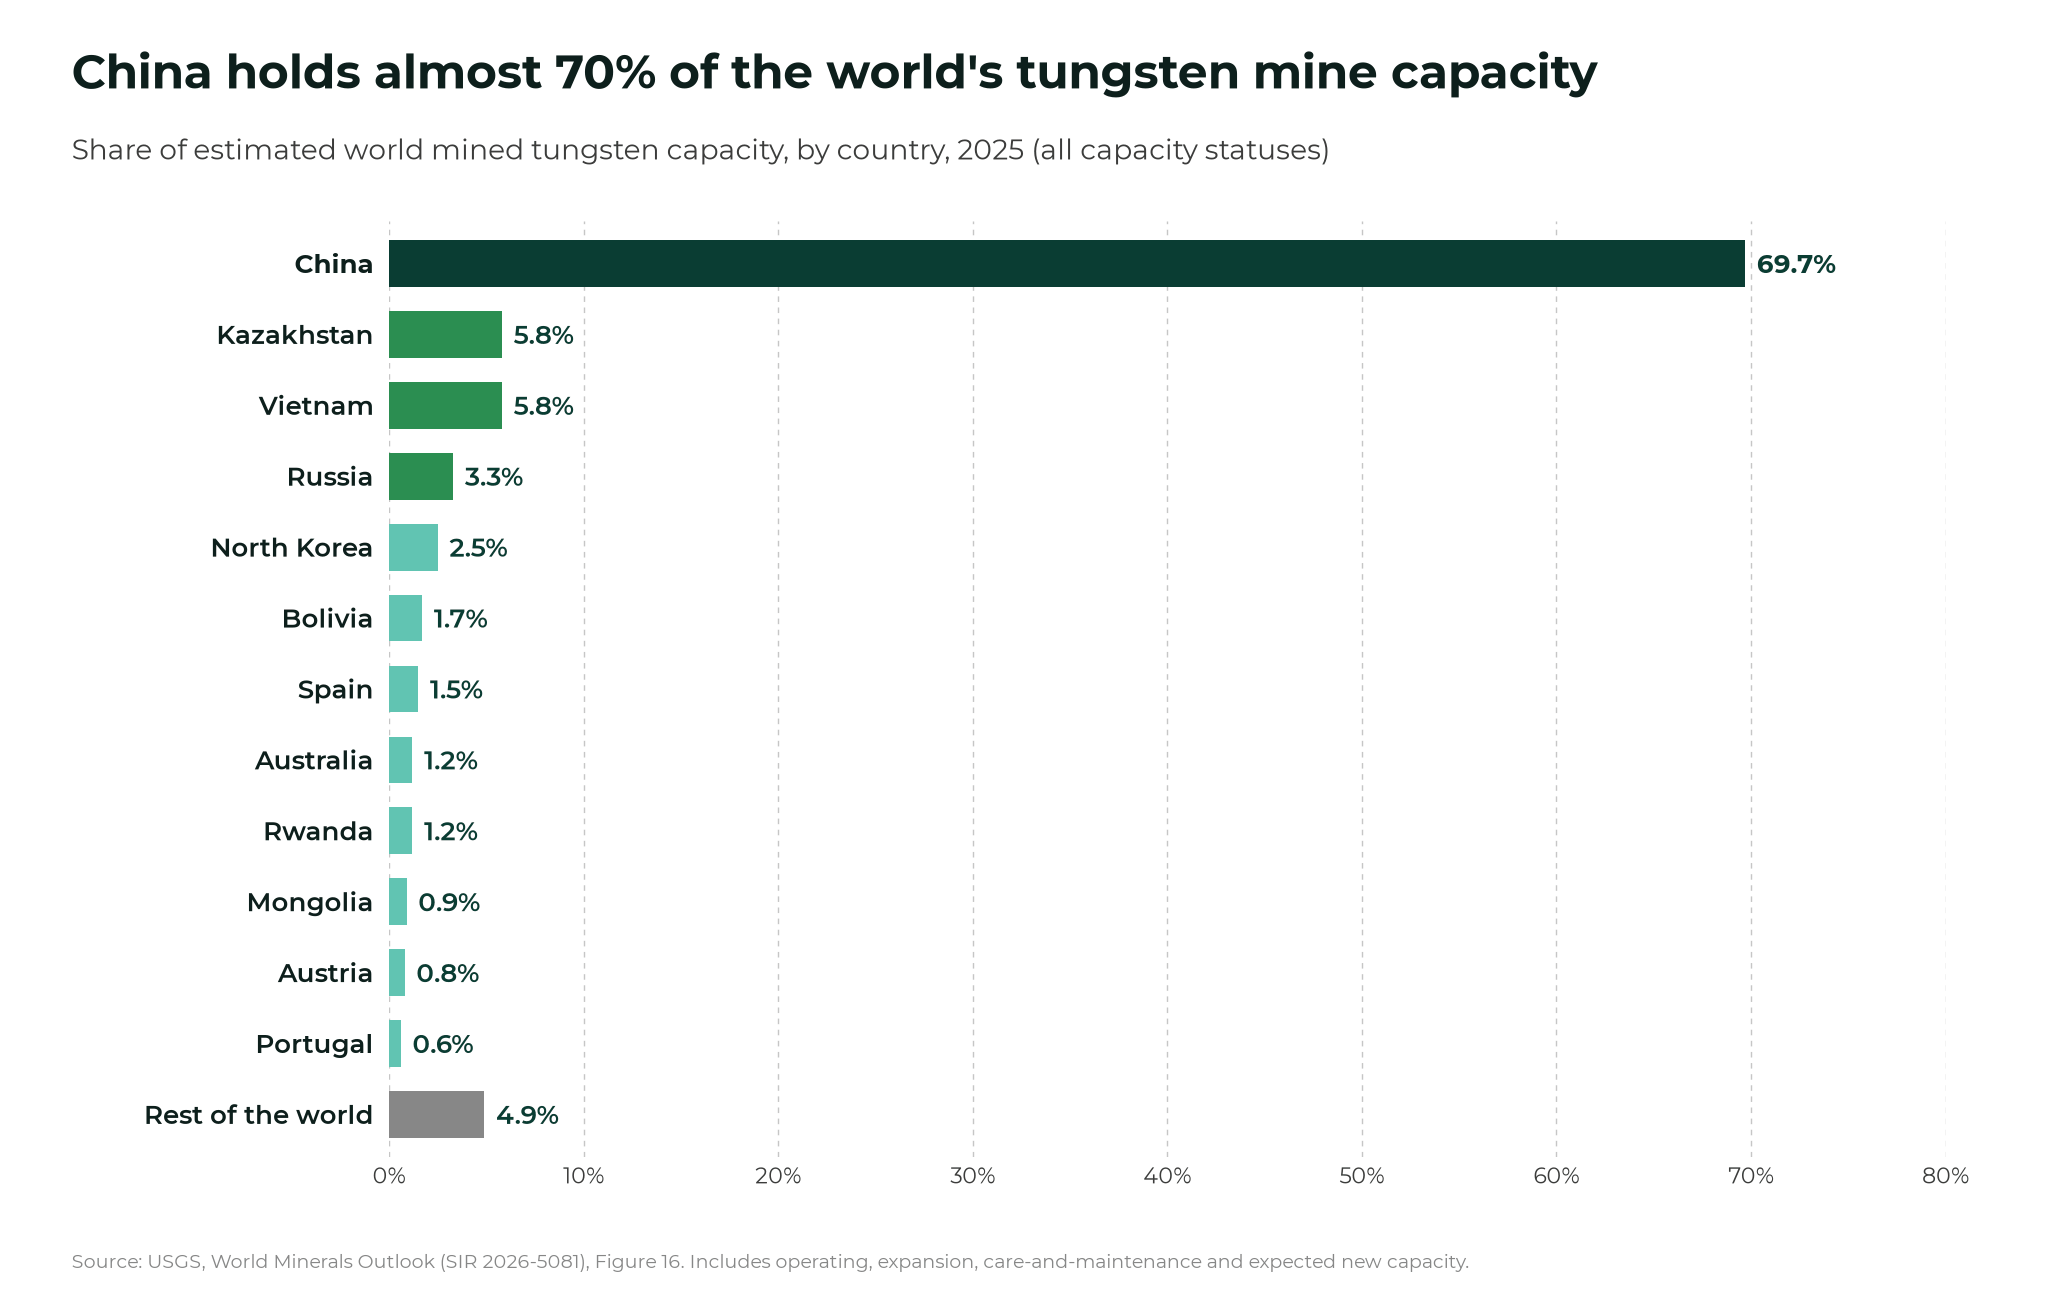
Horizontal bar chart showing China with 69.7% of estimated world tungsten mine capacity in 2025, followed by Kazakhstan and Vietnam at 5.8% each

Antimony, used in ammunition and flame retardants, faces a closer deadline. World antimony mine capacity was 192,000 tonnes in 2025 and is set to grow 6% by 2030, but US antimony metal prices more than doubled from about US$10 a pound in 2024 to US$24 in 2025 after China banned exports to the US (then spot prices fell to about US$12 a pound by the end of April 2026 after Beijing paused the ban in November 2025. That pause runs until 27 November 2026, unless China extends it, as it did on 9 November with its pause on rare earths controls.)

Graphite’s 20% growth meets idle mines

The fastest-growing mineral in the report has the opposite problem. Graphite mine capacity is set to rise about 20% by 2030, but mines used only about 45% of their capacity in 2025.
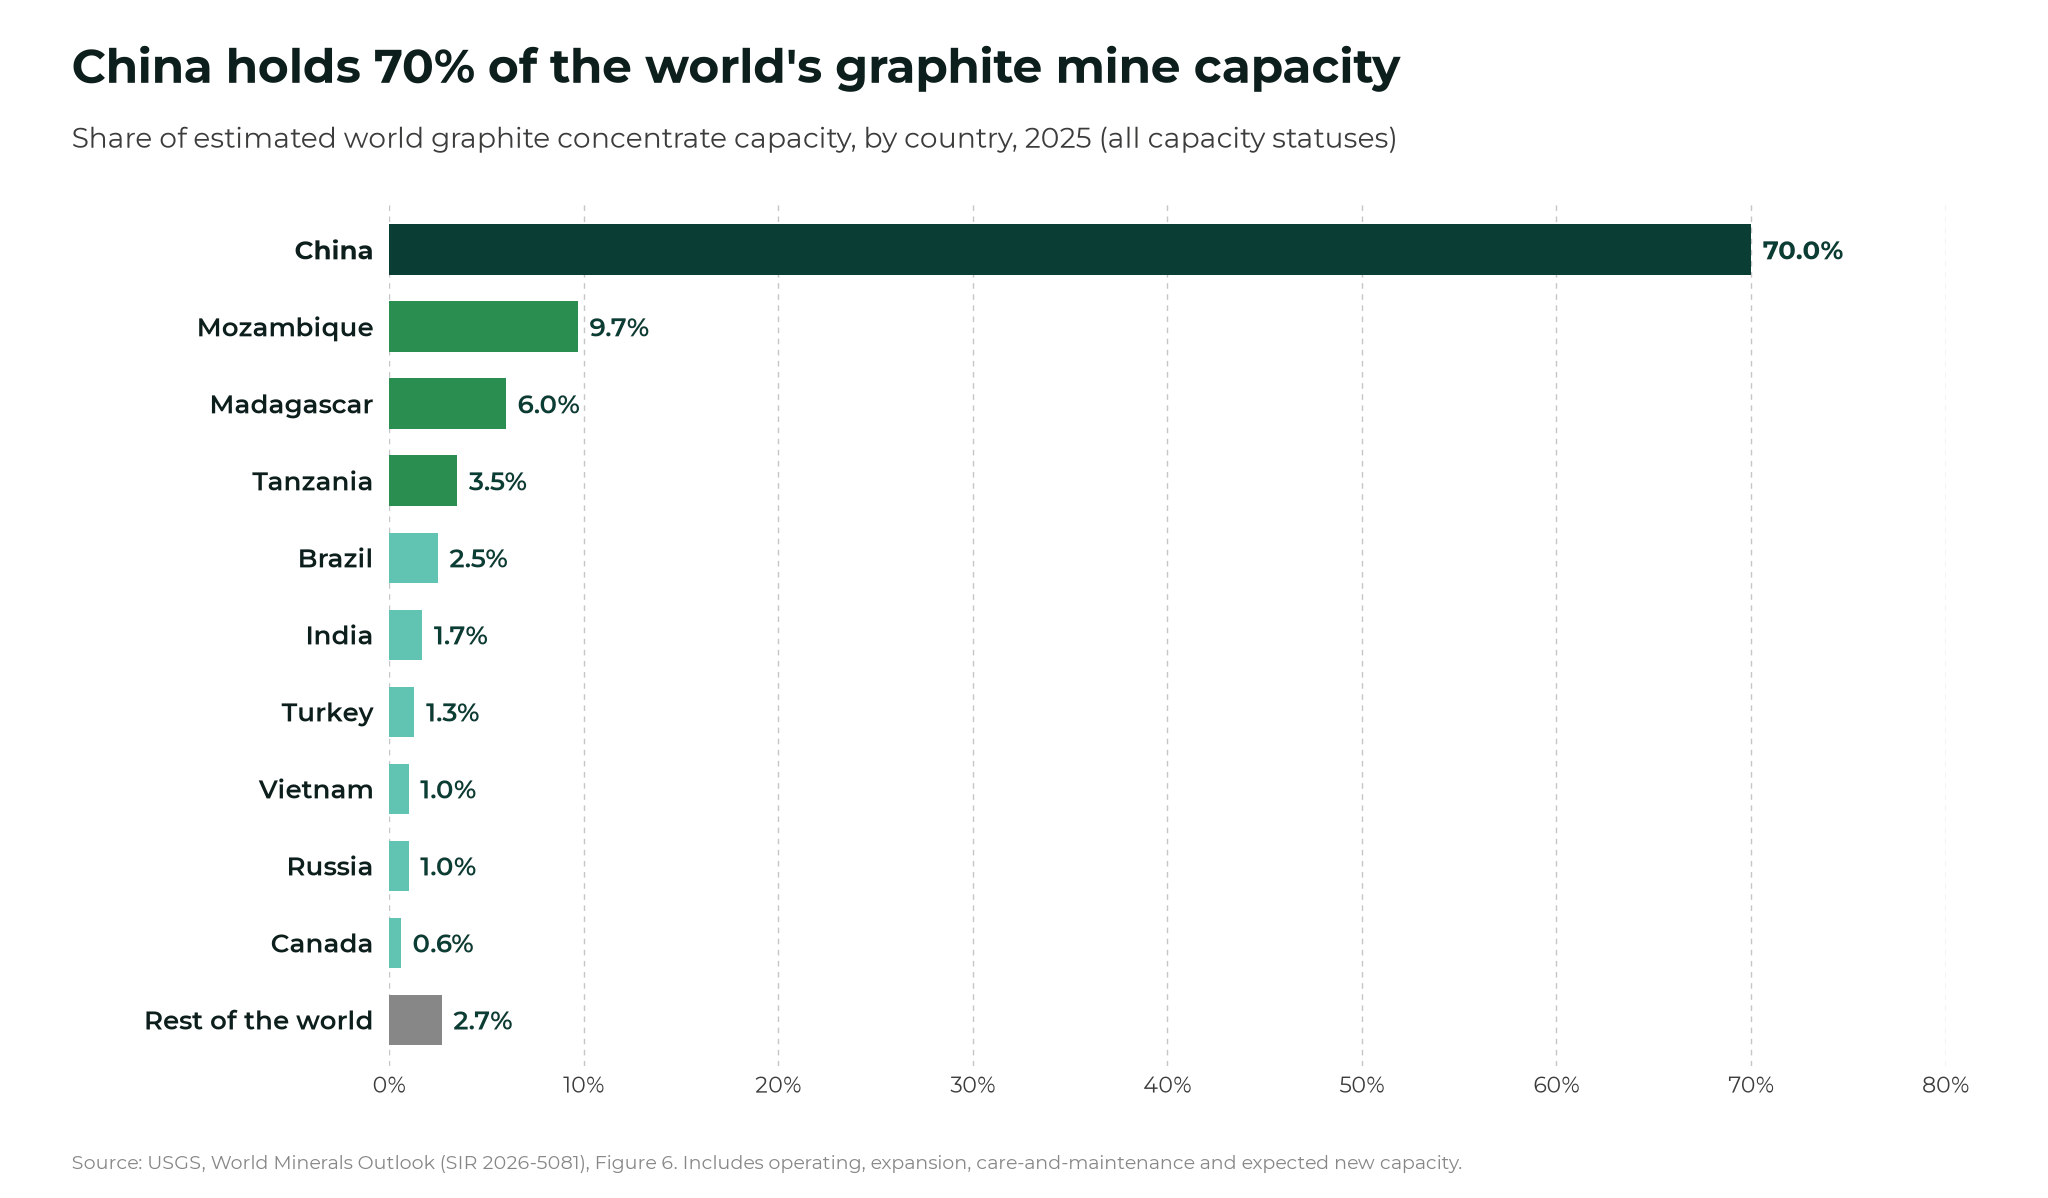
Horizontal bar chart showing China with 70% of estimated world graphite mine capacity in 2025, followed by Mozambique 9.7% and Madagascar 6.0%

Chinese flake graphite capacity grew faster than demand in 2024 and 2025, pushing prices to multiyear lows, and some Chinese producers have run at a loss to hold their market share, with utilisation near 40%. That makes it hard for new mines outside China to compete.

The risks to watch

Capacity is not production.

US metal ore mines ran at about 56% of capacity in 2025, and the USGS says actual output will depend on prices, export controls and how fast projects start. Its tungsten figure is “up to 10 percent (and likely beyond)”.

The USGS figures show that for copper the constraint is time, and for graphite, silicon and tungsten it is China, which can add supply faster than the West can build it and restrict it just as quickly.
Subscribe for Investment Insights. Stay Ahead.

Investment market and industry insights delivered to you in real-time.

Disclaimer

The Oregon Group maintains full editorial control over all content published on this website. While sponsored and advertised placements may be featured, the content remains the sole opinion of The Oregon Group. The author may receive compensation or remuneration for providing content, but all statements and expressions are made independently and are not influenced by sponsors or advertisers. From time to time, The Oregon Group and its directors, officers, partners, employees, authors, or members of their families, as well as persons who are interviewed for articles on this website, may have a long or short position in securities or commodities mentioned and may make purchases and/or sales of those securities or commodities in the open market or otherwise. By accessing and using this website, readers are cautioned to assume that each of the foregoing persons may have a financial interest in all companies and sectors mentioned on this website. Any projections, market outlooks or estimates herein are forward looking statements and are inherently unreliable., and any such statements are based upon certain assumptions and should not be construed to be indicative of the actual events that will occur.  Other events that were not taken into account may occur and may significantly affect the returns or performance of the securities or commodities discussed herein. The information provided herein is based on matters as they exist as of the date of preparation and not as of any future date, and The Oregon Group undertakes no obligation to correct, update or revise the information in this document or to otherwise provide any additional material. The information provided on this website is for informational purposes only and is not, directly or indirectly, an offer, solicitation of an offer and/or a recommendation to buy or sell any security or commodity, and the information provided on this website should not be construed as any advice or an opinion as to the price at which the securities of any company or commodity may trade at any time. The Oregon Group is a publisher of financial information, not an investment advisor.  We do not provide personalized or individualized investment advice or information that is tailored to the needs of any particular recipient, and the information provided on this website is not and should not be construed as personal, financial, investment or professional advice. Readers are cautioned to always do their own research and review of publicly available information and to consult their professional and registered advisors before purchasing or selling any securities or commodities and should not rely on the information contained herein. Neither The Oregon Group nor any of its affiliates accepts any liability whatsoever for any direct or consequential loss howsoever arising, directly or indirectly, from any use of the information contained herein. By using the Site or any affiliated social media account, you are indicating your consent and agreement to this disclaimer and our terms of use. Unauthorized reproduction of this newsletter or its contents by photocopy, facsimile or any other means is illegal and punishable by law.

Share this article

about the author

Picture of The Oregon Group

The Oregon Group

The Oregon Group is an investment research team focused on critical minerals, mining, energy and geopolitics.

Tags

Subscribe Now

Subscribe for in-depth market and industry intelligence you won’t find in the headlines.

Recommended to Read NEXT

GET FREE INVESTMENT INSIGHTS

Investment intelligence and in-depth reports on critical minerals, mining, energy and geopolitics — from capital-markets professionals with boardroom and institutional experience.