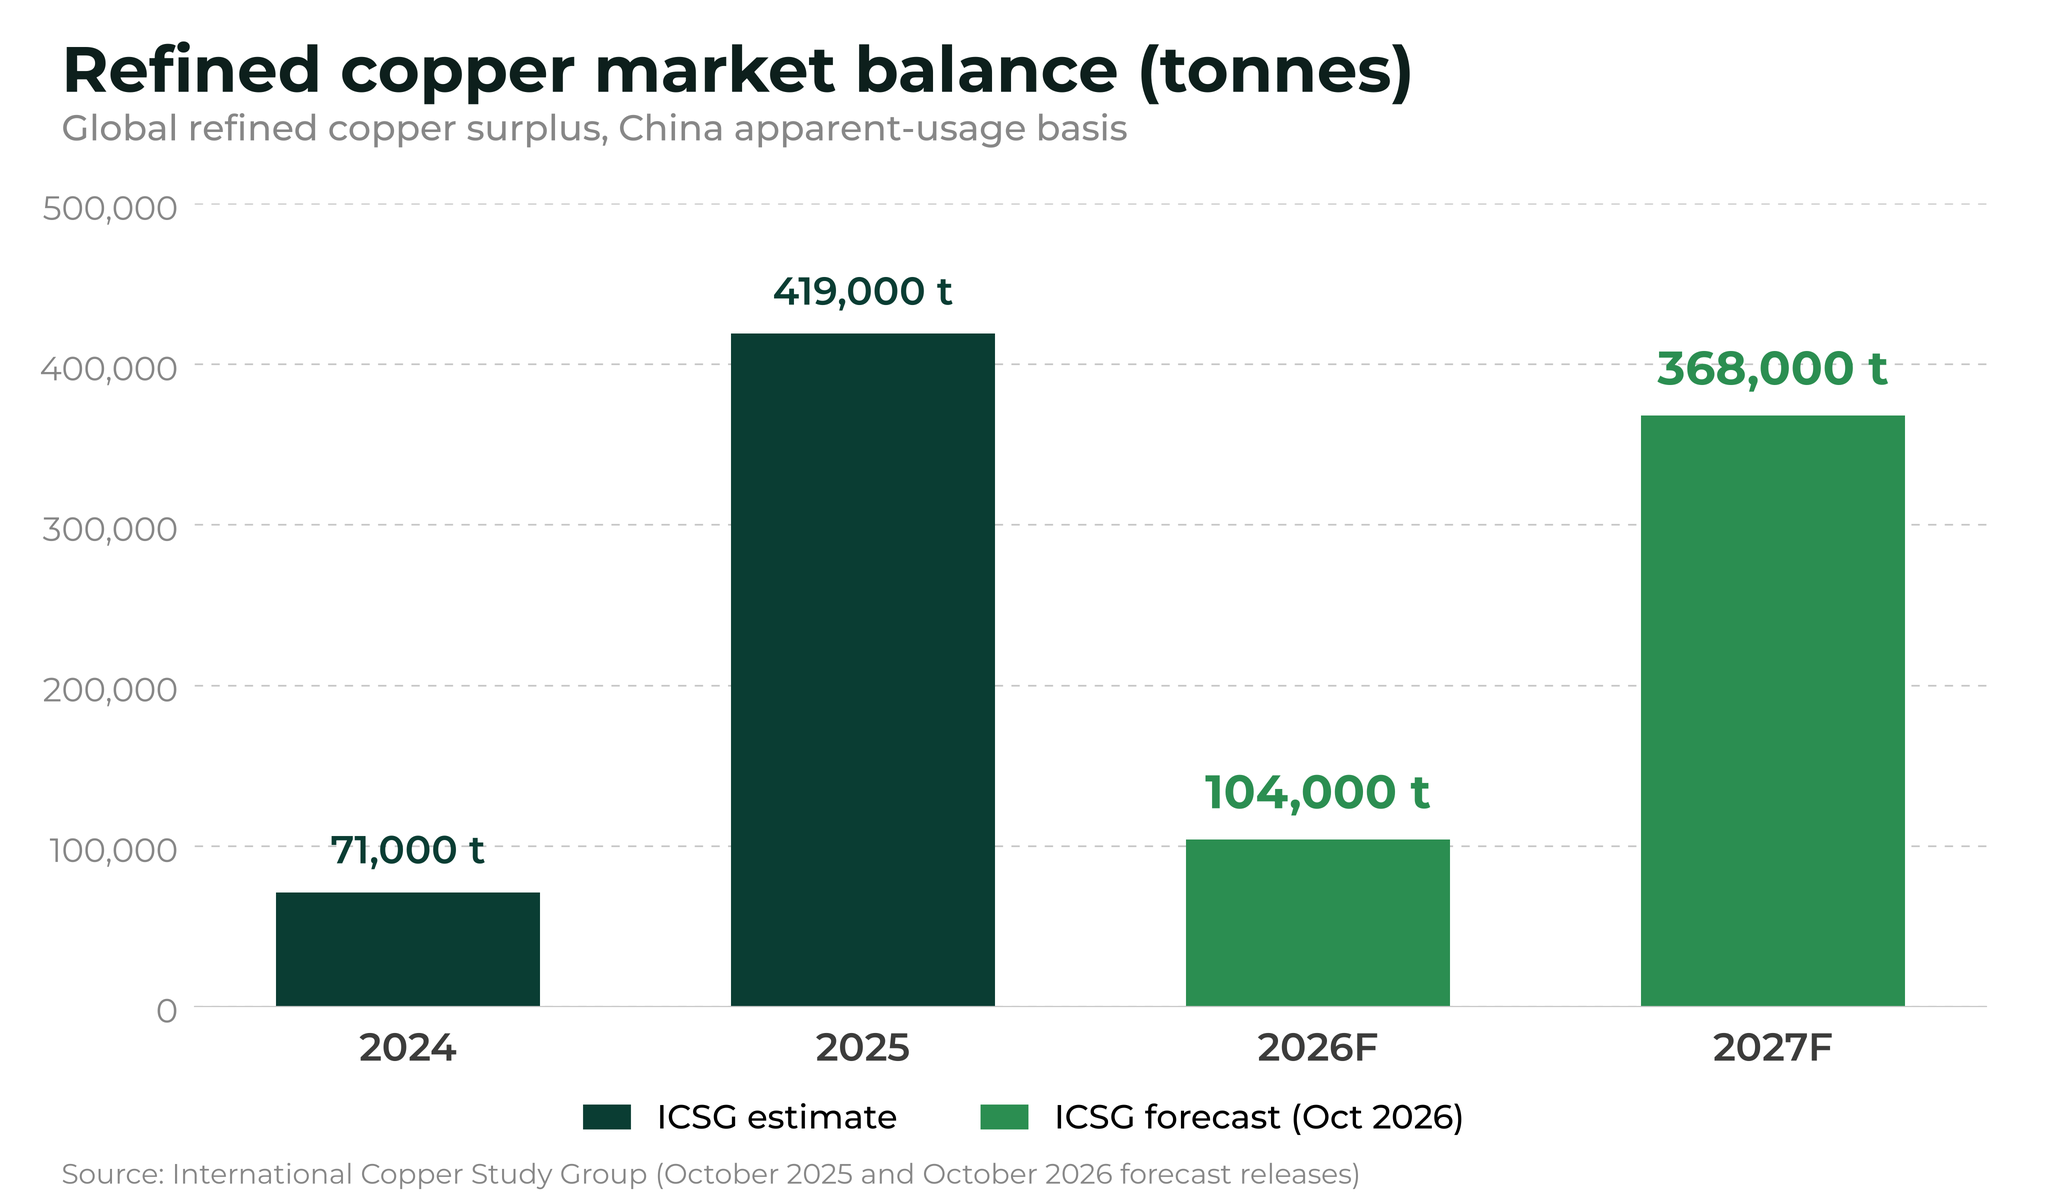
- the global refined copper market is forecast to record a surplus of about 104,000 tonnes in 2026, rising to 368,000 tonnes in 2027
- mine production growth for 2026 was cut to 1.3% from 1.6%, with primary electrolytic refined output expected to decline because concentrate is scarce
- spot copper concentrate treatment charges fell to minus US$272.20 a tonne on October 9 as smelters competed for feed
The global refined copper market is expected to record a surplus of about 104,000 metric tonnes in 2026, rising to 368,000 tonnes in 2027, according to the International Copper Study Group’s latest forecast.
That could weigh on the near-term copper price outlook, but it is less negative for miners than the headline suggests. The 2026 surplus represents only around 0.4% of the 28.59 million tonnes of refined copper ICSG expects the world to consume — and it is also smaller than the 419,000-tonne surplus the group’s tables show for 2025.
More importantly, the surplus comes despite continued constraints in copper concentrates.
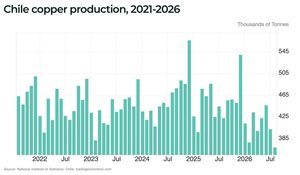
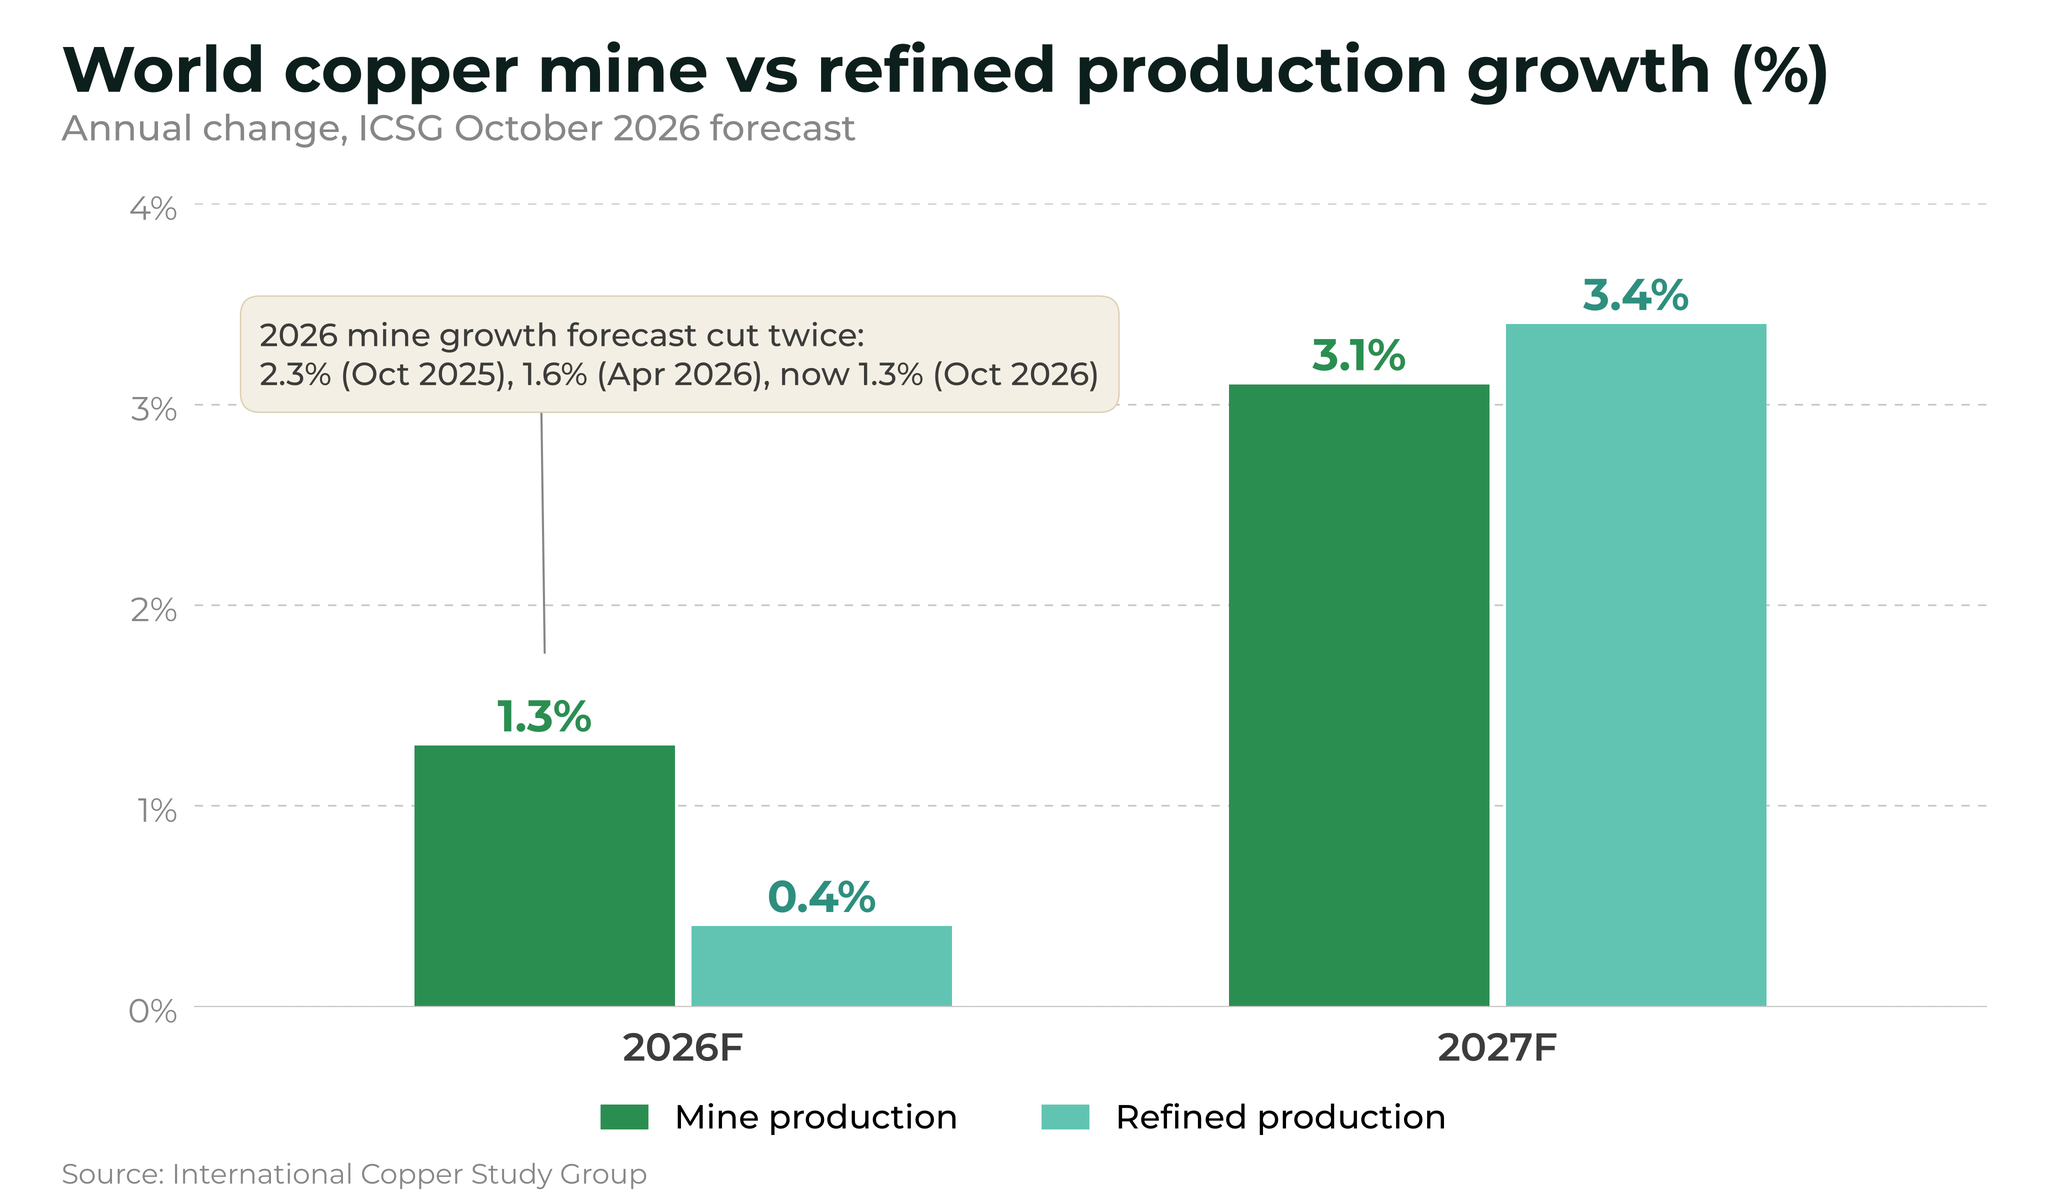
ICSG expects global mine production to grow by just 1.3% in 2026, down from the 1.6% projected in April, attributing the downgrade mainly to downward revisions for Chile, China and Indonesia.
Production at Grasberg in Indonesia and Kamoa-Kakula in the Democratic Republic of Congo remains constrained following incidents in 2025, while ICSG also expects Chilean mine output to decline this year.
Refined surplus does not mean abundant concentrate
ICSG expects total refined production to rise by only 0.4% in 2026. Within that figure, primary electrolytic production is forecast to decline because of constrained concentrate availability.
The decline partially offsets growth in scrap-based secondary and solvent extraction-electrowinning (SX-EW) production. In other words, the refined market can stay in surplus while the supply of newly mined concentrate remains constrained.
Smelter economics point to the same squeeze with Fastmarkets’ Asia-Pacific copper concentrate treatment-charge index falling to minus US$272.20 a tonne on October 9 vs a 2026 benchmark of zero — meaning smelters are effectively paying miners for feed.
For copper miners able to deliver reliable concentrate, that distinction matters: recycling and alternative refining routes are helping bridge a weak year for primary supply.
Demand continues to grow
ICSG expects refined copper usage to increase by 1.5% in 2026 and accelerate to 2.5% in 2027. For example, Chinese apparent usage is forecast to grow by 2.5% this year, while usage outside China is expected to remain essentially unchanged.
Consumption should continue to be supported by improving manufacturing activity in some end-use sectors, the energy transition, urbanisation, digitalisation — including data centres and artificial intelligence — and new semi-fabricated copper product capacity.
ICSG did, however, trim its 2026 usage forecast for the Middle East, North America and the EU.
The 2027 forecast requires mines to deliver
The larger 2027 surplus assumes global mine output growth accelerates to 3.1%.
That depends on continued ramp-ups at new and expanded operations, improved output in Chile and Zambia, and a continued recovery of operating rates in Indonesia and the DRC.
The forecast therefore relies on project execution, but the ICSG has already cut 2026 mine growth twice, from the 2.3% it expected in October 2025 to 1.6% in April and 1.3% now. And primary copper mine supply continues to see declining ore grades and disruption.
ICSG also cautions that actual balances have recently deviated from its forecasts because of unforeseen developments. For example, its Chinese demand figure excludes changes in unreported stocks, which can materially alter the global balance.
The 368,000-tonne surplus forecast for 2027 would equal approx 1.3% of expected 2027 consumption of 29.31 million tonnes which is less than a third of the 1.26 million tonnes Escondida produced in BHP’s 2026 financial year.
The refined surplus could limit near-term price upside, particularly if the expected 2027 mine recoveries arrive on schedule, but scarce concentrate and the forecast’s dependence on multiple ramp-ups favour producers with reliable output. The next signal is whether miners and smelters agree a 2027 treatment-charge benchmark during LME Week.