- US President Donald Trump said the Quad (the US, Japan, India and Australia) signed “several important, new critical mineral deals” in Manila on November 17, but no minerals, companies or values were made public
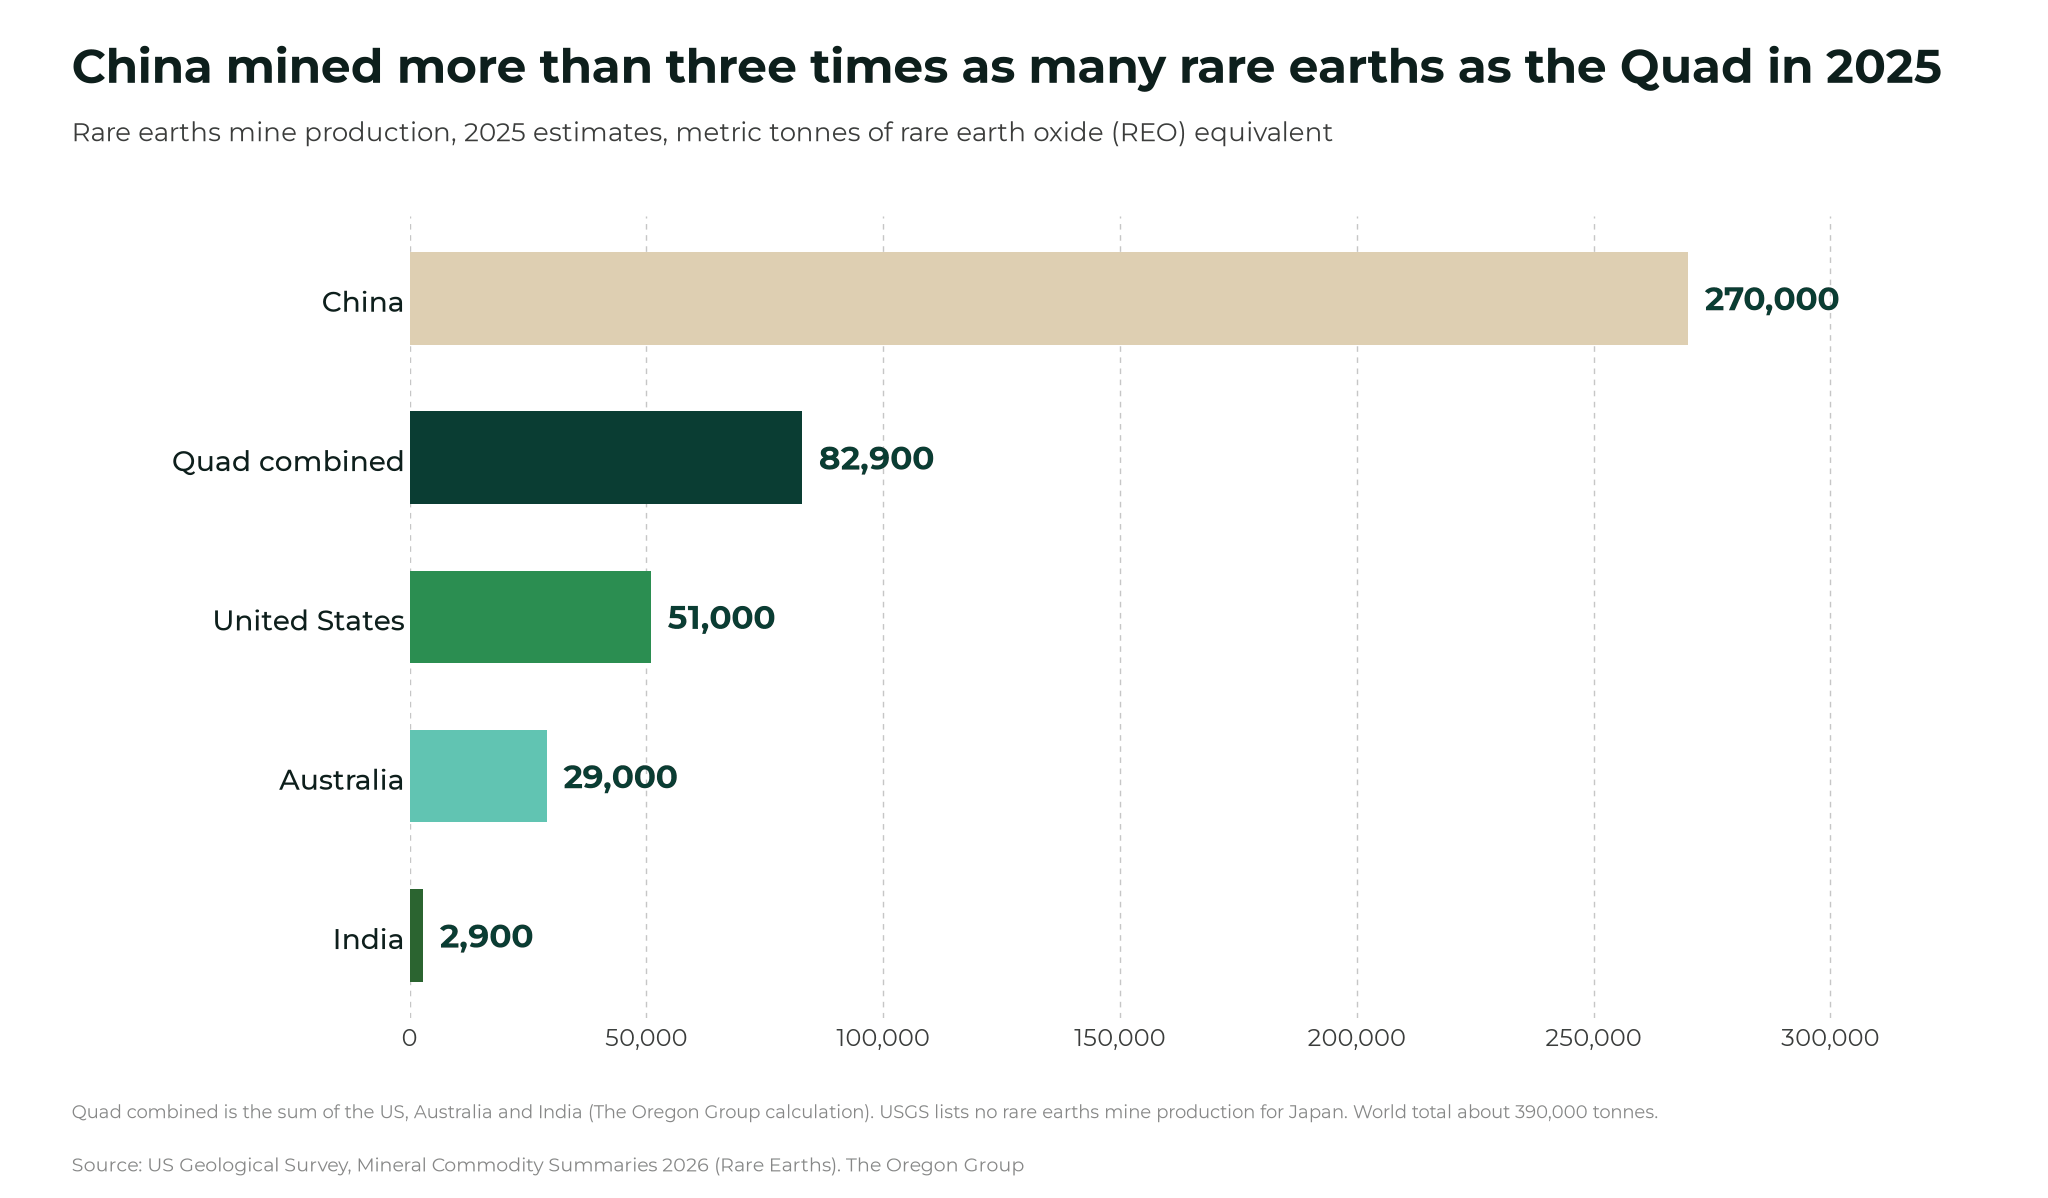
- Trump also said the US will catch China on rare earths “within 10 months”, yet US mines produced 51,000 tonnes of rare earth oxide in 2025, against China’s 270,000 tonnes, less than a fifth as much
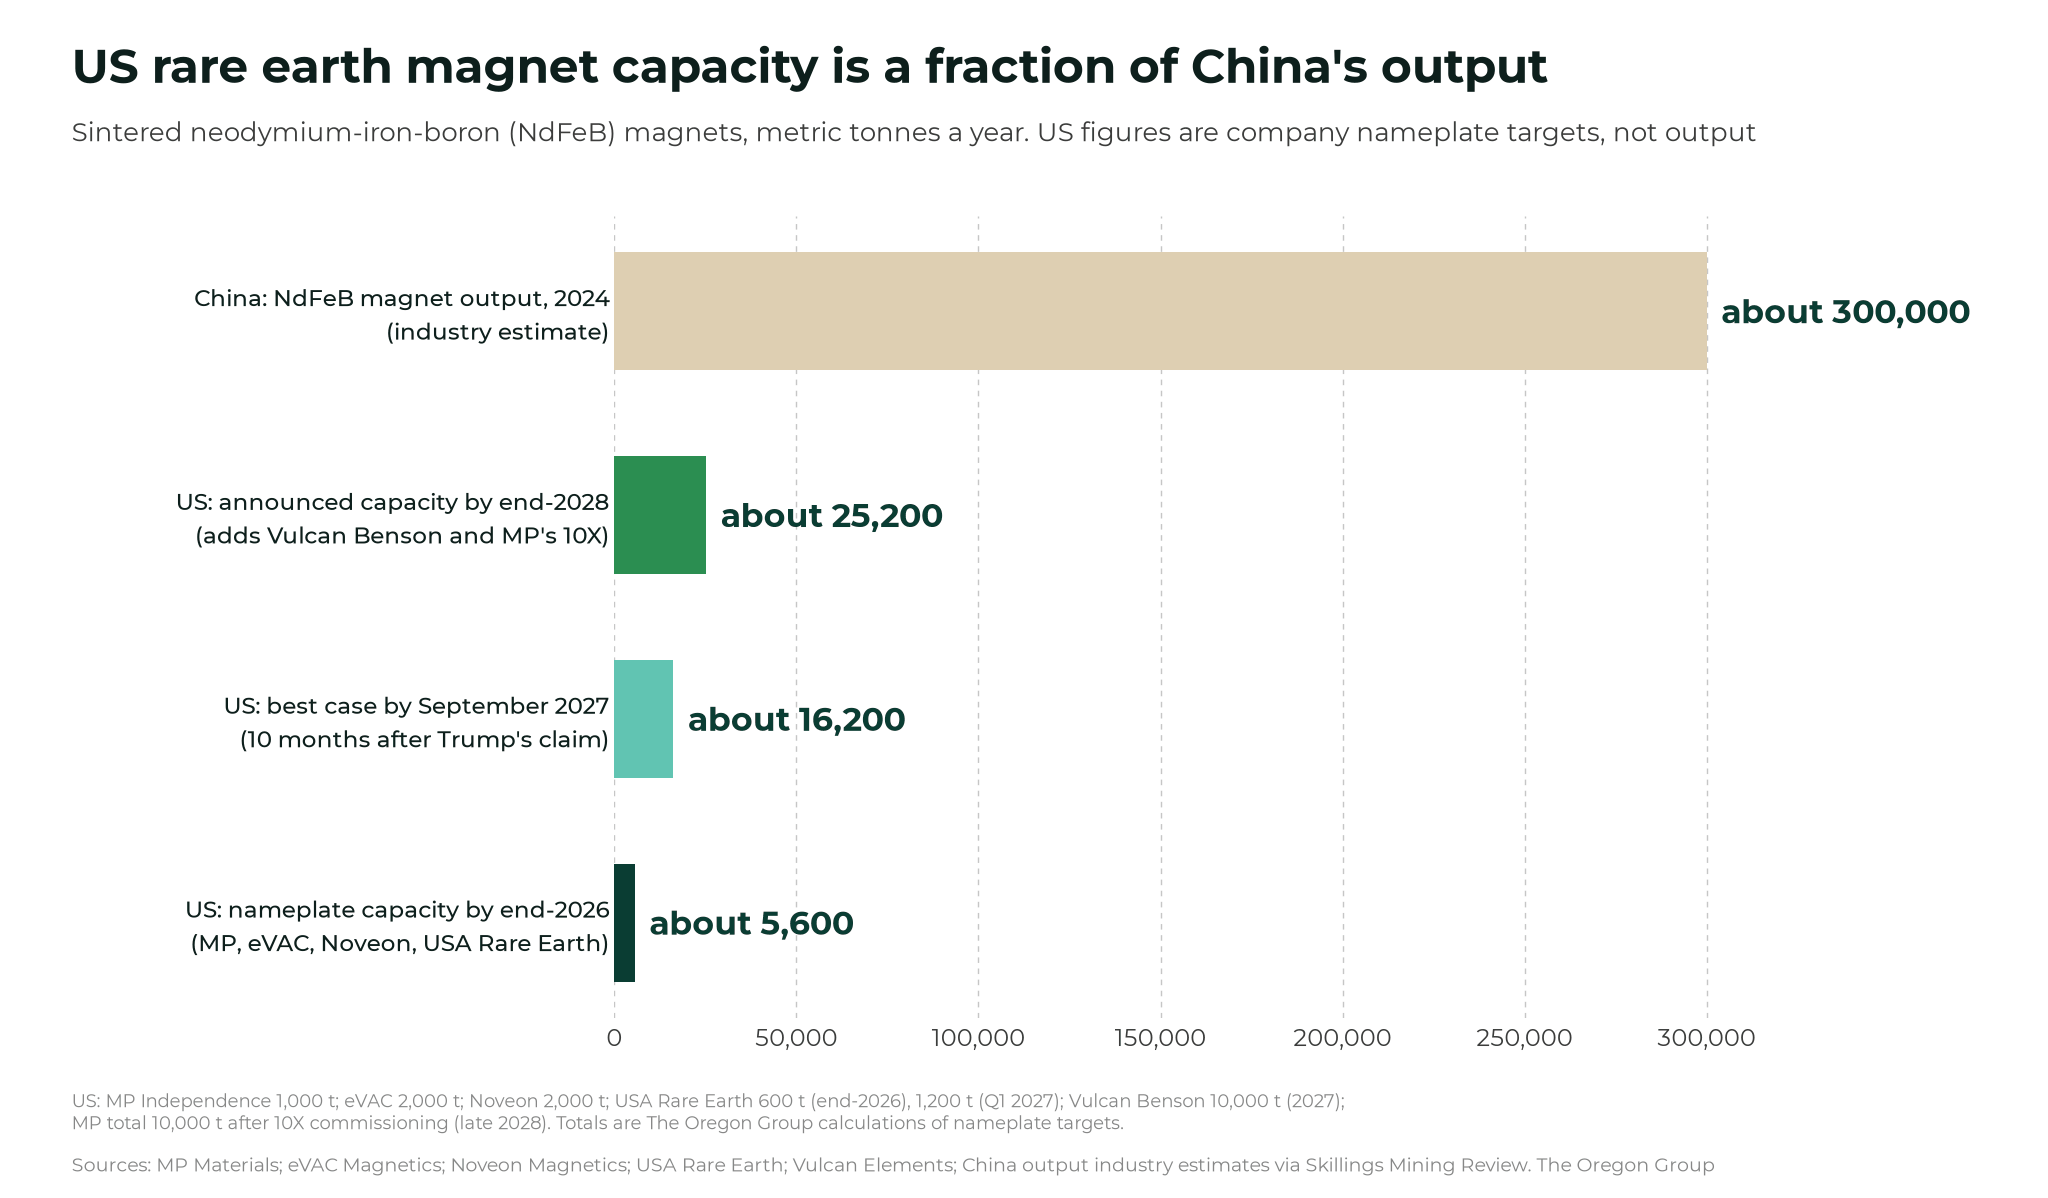
- in magnets the gap is wider: US plants are targeting about 5,600 tonnes a year of capacity by the end of 2026, against about 300,000 tonnes of Chinese output, and China separates 97% of the world’s dysprosium and terbium oxide, the heavy rare earths that let magnets work at high temperatures
US President Donald Trump says the US will catch China on rare earths within 10 months, after the Quad partners signed what he called several new critical mineral deals at their summit in Manila on Tuesday.
He made the claim to reporters before meeting Indian Prime Minister Narendra Modi, Japanese Prime Minister Sanae Takaichi and Australian Prime Minister Anthony Albanese, in the first Quad leaders’ meeting of his second term. President Donald Trump said:
And he went further: “Everything that we need we’ll have in 10 months.”
The announcement comes as Trump begins a three-day Asian trip, weeks after his Republican Party suffered heavy losses in the midterm elections; he landed in Shenzhen on Wednesday for the Asia-Pacific Economic Cooperation (APEC) summit, where he is expected to meet Chinese President Xi Jinping before a first three-way meeting with Xi and Russian President Vladimir Putin on Thursday.
What the Quad actually agreed on rare earths
Trump said the new deals would “secure our supply chains and ensure that none of our nations is vulnerable to coercion by any single foreign supplier”.
However, Trump did not specifically name China, and he did not say what had been signed, with whom, or for how much. The leaders’ joint press release also does not mention rare earths or critical minerals by name, and instead expresses “grave concerns about economic coercion, including through arbitrary export restrictions” and says “we are securing critical supply chains”. Japan’s summary adds only that the four leaders confirmed they “will work together on critical minerals supply chain resilience”.
The summit’s published outcomes lay elsewhere, for example:
- a first Quad exercise for P-8 and P-3C maritime patrol aircraft in 2027
- the first Quad Business Leaders’ Forum, in Mumbai in early 2027
- enhanced cybersecurity cooperation, and an expansion of Australia’s undersea cable work to cover electricity cables
The investment so far still sits in earlier commitments. In May, the four countries said they intend to mobilise up to US$20 billion in government and private support for mining, processing and recycling, “through new and existing efforts”. That framework says the partners will consider “price mechanisms” against unfair trade practices, but it sets no price floor, stockpile or list of projects.
In October, Quad foreign ministers in Atlanta welcomed a US$10 million US commitment to recover critical minerals from electronic waste in India and Southeast Asia. The Quad’s export credit agencies, the state lenders that finance exports and overseas projects, meet in Tokyo on November 18 to look for practical cooperation.
In other words, the Quad has a framework and a funding ambition, but no published rare earths project, offtake or price floor of its own yet.
Why the Quad matters for rare earths supply
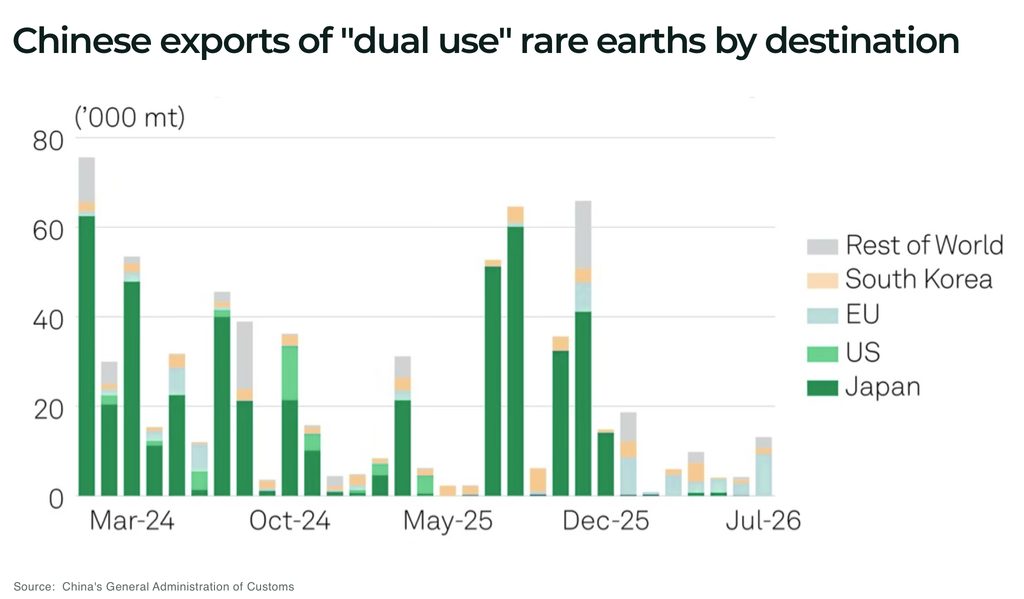
China has effectively shut off exports of some critical minerals to Japan for nearly a year, and in October, as we reported, Japan was months away from running out of yttrium, one of the heavy rare earths China restricts.
Each member brings a different part of the supply chain. Modi put it plainly:
Some of this coordination already exists bilaterally, with Japan and Australia jointly taking output from Lynas Rare Earths, the US and Australia have both invested in Arafura and Australian Strategic Materials, and the three back the Alcoa-Sojitz gallium plant in Western Australia, expected to supply 10% of the world’s gallium.
Washington has put up the the majority of capital so far, with reportedly more than US$27 billion committed or conditionally committed to critical minerals projects since Trump’s inauguration. Albanese said that since his critical minerals agreement with Trump, “we’re seeing that investment begin to flow into Australia”.
How many rare earths does the US actually make?
The US is mining more rare earths than before, with US mines produced an estimated 51,000 tonnes of rare earth oxide (REO) in 2025, up from 45,500 tonnes in 2024, mostly from MP Materials’ Mountain Pass mine in California.
But, China mined 270,000 tonnes over the same period, out of a world total of about 390,000 tonnes so, even with Australia and India added, the Quad mined less than a third as much as China.
And then there’s the processing of the ore.
The International Energy Agency (IEA) estimates that in 2024 China accounted for 60% of mined magnet rare earths, 91% of refined output and 94% of sintered permanent magnet production.
Separation: the US is growing quickly from a small base. Domestic output of separated rare earth compounds and metals rose to an estimated 8,900 tonnes in 2025, from 4,300 tonnes in 2024 and 120 tonnes in 2021. MP produced 1,018 tonnes of neodymium-praseodymium (NdPr) oxide, the main magnet ingredient, in the third quarter, up 41% on a year earlier.
Magnets: the US has four operating or ramping plants for neodymium-iron-boron (NdFeB) magnets, the strongest permanent magnets, used in electric vehicles, wind turbines, drones and missiles, for example:
- MP’s Independence plant in Fort Worth, Texas, designed for about 1,000 tonnes a year, which completed General Motors’ qualification and starts saleable deliveries this quarter
- eVAC Magnetics in Sumter, South Carolina, which targeted 2,000 tonnes a year of capacity by the first quarter of 2026
- Noveon Magnetics in San Marcos, Texas, building up to its current capacity of 2,000 tons a year and raising US$215 million to expand beyond it
- USA Rare Earth in Stillwater, Oklahoma, targeting a 600-tonne annual run rate by the end of 2026 and 1,200 tonnes in the first quarter of 2027
Together that is about 5,600 tonnes a year of nameplate capacity, before ramp-up problems, against about 300,000 tonnes of NdFeB magnets made in China in 2024, on industry estimates. MP’s own chief executive, James Litinsky, puts the global NdFeB market at roughly 250,000 tonnes a year, “with well over 90% of production concentrated in China”.
On either measure, US magnet capacity is roughly 2% of China’s output.
Heavy rare earths: the narrowest bottleneck is dysprosium and terbium, which high-temperature magnets in motors and weapons need. China accounted for 97% of separated dysprosium and terbium oxide in 2026, according to Benchmark Mineral Intelligence. MP says commercial-scale production of both starts this quarter, mainly for its own magnets.
Can the US catch China in 10 months?
Ten months from the summit is September 2027, so it seems highly unlikely that the US will “catch” China on any published plan — however, the priority for the US is to relieve the national security concerns and supply bottle neck from China.
So, by 2027, the largest new US plant, Vulcan Elements’ US$1 billion factory in Benson, North Carolina, should be starting up: it is designed for 10,000 tonnes a year of magnets, with commissioning due in 2027. Even if it and every other plant were running at nameplate by September 2027, US capacity would be about 16,200 tonnes a year, on our calculations.
MP’s 10X plant in Northlake, Texas, would lift its total US magnet capacity to about 10,000 tonnes, but it is scheduled for commissioning in late 2028. With 10X, announced US capacity reaches about 25,200 tonnes a year, roughly a tenth of China’s estimated 2024 output.
However, in mining, to match China, US mine output would need to rise more than fivefold, and no new large US rare earths mine is due to open within 10 months.
Jack Lifton, co-chairman of the Critical Minerals Institute, a Toronto-based think tank, argues that money alone cannot close the gap:
The opportunity is in defence supply, not parity
A narrower reading of Trump’s claim is more defensible. “Everything that we need” could mean the qualified, non-Chinese magnets the US military and its contractors need, not China’s full output.
And that target has a hard deadline as, from January 1, 2027, Pentagon rules extend the ban on Chinese material to the full mine-to-magnet chain, and suppliers have warned that new supply can take up to 10 years to build and certify.
Washington has also made non-Chinese supply financeable. The Pentagon’s deal with MP sets a 10-year price floor of US$110 a kilogram for NdPr and commits that all 10X magnets will be bought for 10 years by defence and commercial customers. MP booked US$8.1 million of price protection income in the third quarter under that floor.
Price floors, guaranteed buyers and a defence deadline give US and allied producers with separation capacity, heavy rare earths and qualified magnets a protected market, whatever China’s output does.
The risks to watch
China’s pause on its October 2025 rare earths export controls now runs only to January 10, 2027, and its April 2025 licences on dysprosium, terbium and other heavy rare earths remain in force. US imports of rare earth compounds and metals from China have averaged almost 75% below pre-restriction levels since the Busan truce, according to the Center for Strategic and International Studies (CSIS).
Beijing has also targeted the US champions directly. Since June 22, MP Materials and USA Rare Earth have been on China’s export control list, which bars anyone from supplying them with Chinese-origin dual-use items. This week’s talks with Xi in Shenzhen will show whether Beijing extends the truce or tests the Quad’s new resolve.
The Quad’s own commitments are also non-binding. The May framework uses “intend” and “up to”, and none of the Manila deals has been published.
The Quad can help the US build a rare earths supply chain that China cannot switch off, but on published plans, catching China is a project for the next decade, not the next 10 months.