Critical Minerals and Energy Intelligence

China’s gold imports top 1,000 tonnes, highest January-August total since 2017

China imported more than 1,000 tonnes of gold in the first eight months of 2026, exceeding its purchases for the whole of last year — with imports reaching their highest level for the period in customs records dating back to 2017.

Lower international prices and a stronger yuan encouraged purchases and investment demand, while Chinese gold prices traded above global benchmarks, drawing metal into the country.
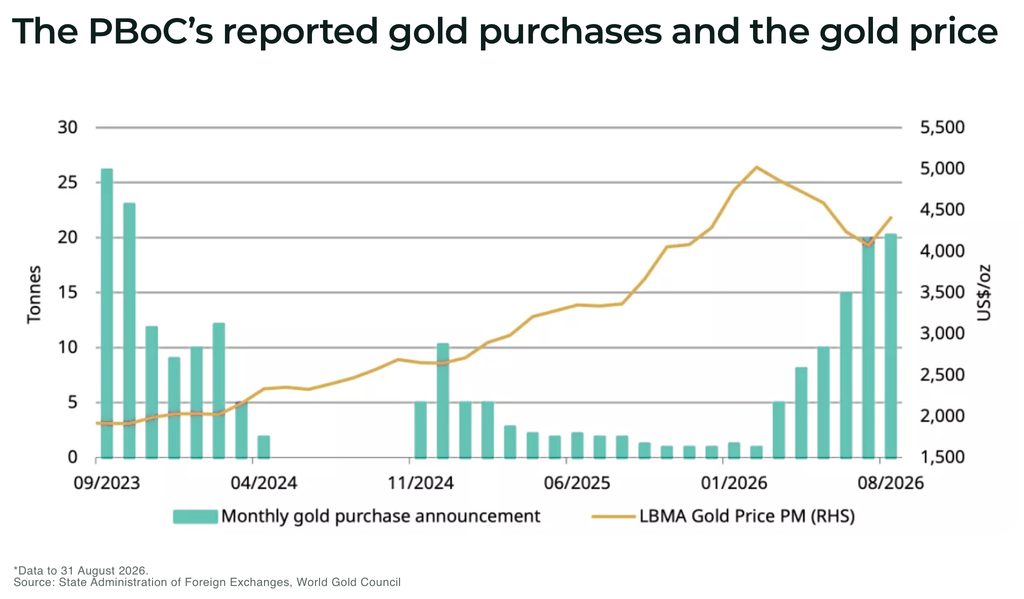
The PBoCs reported gold purchases and the gold price - The Oregon Group

The import bill reached US$158.8 billion, compared with US$96.5 billion for 886 tonnes across all of 2025, according to Financial Times figures reported by International Finance.

The two major sources of buying include:

  • Central-bank reserves: the People’s Bank of China added 20.2 tonnes in August, its largest monthly purchase since October 2023. Its 22nd consecutive monthly increase lifted official holdings to 2,387 tonnes, equivalent to 9% of foreign-exchange reserves
  • Investment funds: Chinese gold ETFs added 11 tonnes in August, taking holdings to 293 tonnes. Inflows continued into early September, supported by falling domestic bond yields and sluggish equities
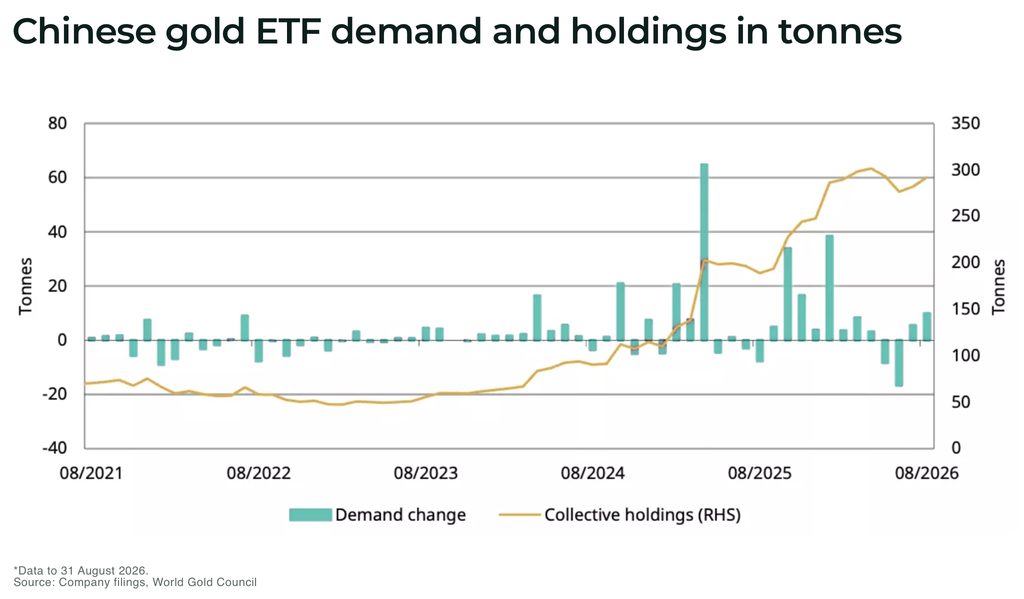
Chinese gold ETF demand and holdings in tonnes - The Oregon Group

Official reserve additions and commercial imports are separate measures; the 1,000-tonne import figure should not be read as central-bank buying.

The scale is substantial: China’s eight-month imports exceeded a quarter of the approx 3,672 tonnes mined worldwide in 2025, when mine production grew just 1%. Imports can also include recycled metal and existing inventories.

However, physical demand softened in August. Shanghai Gold Exchange withdrawals fell 22% month-on-month and 27% year-on-year to 62 tonnes, reflecting cooler bullion investment and weak jewellery demand.

For gold investors and miners, the figures suggest continued support from reserve diversification and investment flows. Sustained Chinese buying could help absorb selling elsewhere, although August’s wholesale slowdown shows that buyers remain sensitive to price and volatility.
Subscribe for Investment Insights. Stay Ahead.

Investment market and industry insights delivered to you in real-time.

Disclaimer

The Oregon Group maintains full editorial control over all content published on this website. While sponsored and advertised placements may be featured, the content remains the sole opinion of The Oregon Group. The author may receive compensation or remuneration for providing content, but all statements and expressions are made independently and are not influenced by sponsors or advertisers. From time to time, The Oregon Group and its directors, officers, partners, employees, authors, or members of their families, as well as persons who are interviewed for articles on this website, may have a long or short position in securities or commodities mentioned and may make purchases and/or sales of those securities or commodities in the open market or otherwise. By accessing and using this website, readers are cautioned to assume that each of the foregoing persons may have a financial interest in all companies and sectors mentioned on this website. Any projections, market outlooks or estimates herein are forward looking statements and are inherently unreliable., and any such statements are based upon certain assumptions and should not be construed to be indicative of the actual events that will occur.  Other events that were not taken into account may occur and may significantly affect the returns or performance of the securities or commodities discussed herein. The information provided herein is based on matters as they exist as of the date of preparation and not as of any future date, and The Oregon Group undertakes no obligation to correct, update or revise the information in this document or to otherwise provide any additional material. The information provided on this website is for informational purposes only and is not, directly or indirectly, an offer, solicitation of an offer and/or a recommendation to buy or sell any security or commodity, and the information provided on this website should not be construed as any advice or an opinion as to the price at which the securities of any company or commodity may trade at any time. The Oregon Group is a publisher of financial information, not an investment advisor.  We do not provide personalized or individualized investment advice or information that is tailored to the needs of any particular recipient, and the information provided on this website is not and should not be construed as personal, financial, investment or professional advice. Readers are cautioned to always do their own research and review of publicly available information and to consult their professional and registered advisors before purchasing or selling any securities or commodities and should not rely on the information contained herein. Neither The Oregon Group nor any of its affiliates accepts any liability whatsoever for any direct or consequential loss howsoever arising, directly or indirectly, from any use of the information contained herein. By using the Site or any affiliated social media account, you are indicating your consent and agreement to this disclaimer and our terms of use. Unauthorized reproduction of this newsletter or its contents by photocopy, facsimile or any other means is illegal and punishable by law.

Share this article

about the author

Picture of The Oregon Group

The Oregon Group

The Oregon Group is an investment research team focused on critical minerals, mining, energy and geopolitics.

Tags

Subscribe Now

Subscribe for in-depth market and industry intelligence you won’t find in the headlines.

Recommended to Read NEXT

GET FREE INVESTMENT INSIGHTS

Investment intelligence and in-depth reports on critical minerals, mining, energy and geopolitics — from capital-markets professionals with boardroom and institutional experience.