Critical Minerals and Energy Intelligence

EY ranks harder-to-run mines as mining’s top risk for 2027


Mines getting harder to run is the mining industry’s biggest risk for 2027, according to EY’s Top 10 business risks and opportunities for mining and metals in 2027.

The ranking is based on around 400 responses from executives at mining and metals companies with at least US$1 billion in revenue, surveyed in June-July 2026.

EY blames ageing deposits, more variable ore grades and slow regulatory approvals — “Older mines are tougher and more expensive to mine,” it said.

The ranking comes as Chile, the world’s largest copper producer, cut its 2026 copper output forecast for the third time this year.
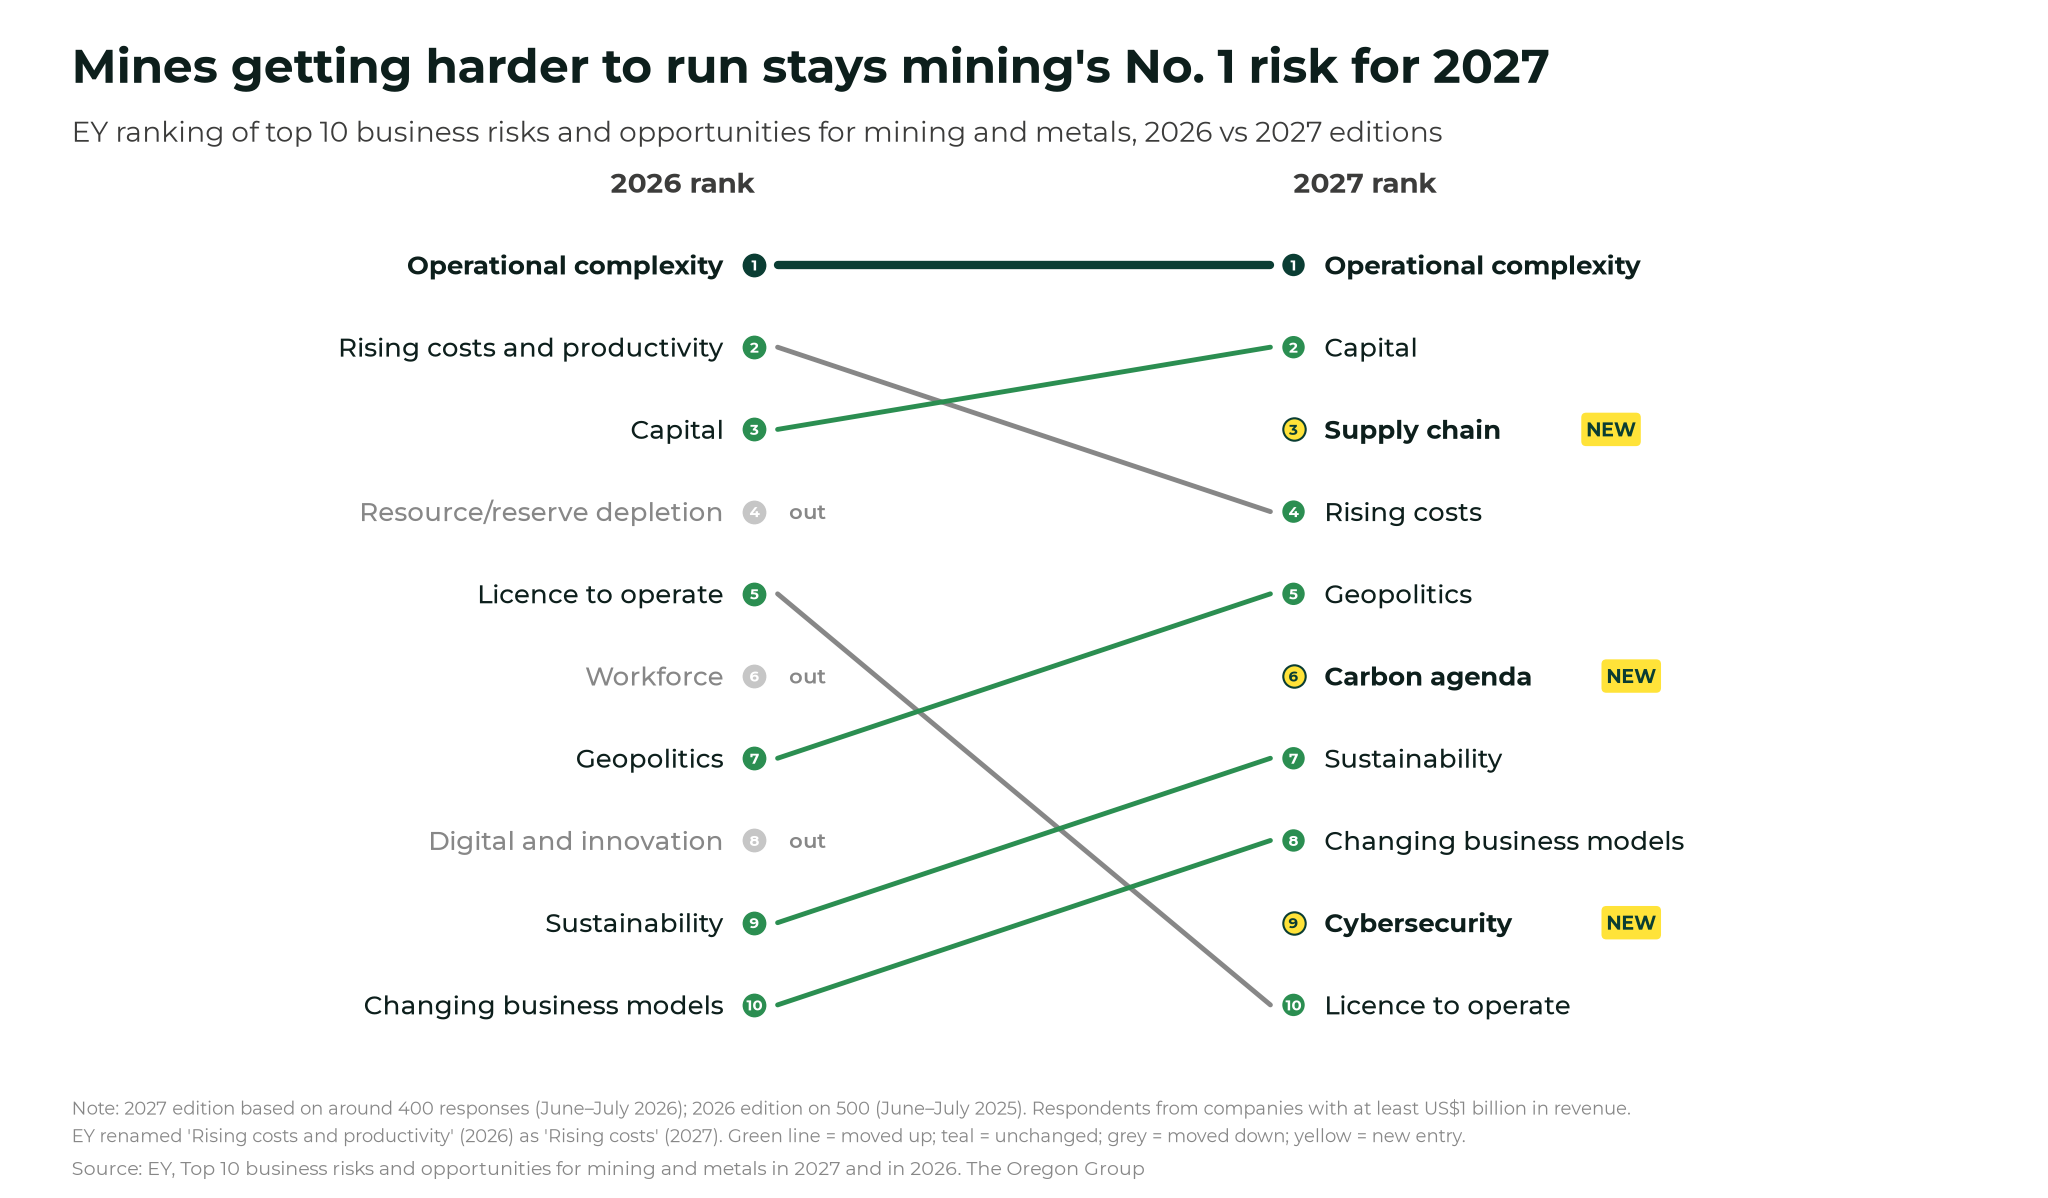
Slope chart comparing EY's top 10 business risks for mining and metals in 2026 and 2027, with operational complexity ranked first in both years and supply chain, carbon agenda and cybersecurity entering the 2027 list

What is slowing mines down

The biggest challenges to running mines include:

  • regulatory compliance delays were the most cited bottleneck to production throughput, named by 30.5% of respondents
  • reserve grade variability followed at 29.3%, ahead of material handling inefficiencies at 26.3%. Respondents could pick three issues
  • labour availability (26.0%), approval and permitting delays (25.8%) and processing plant capacity (25.5%) were close behind

And EY’s global mining and metals leader says the problem is getting worse, with Paul Mitchell, EY’s global mining and metals leader, saying in a statement.

“Mining has always been complex, but the degree of operational complexity is increasing as mines age and reserves are depleted and the new ones are more difficult to mine and process.”

The decline is a long-running problem; for example, in last year’s edition, EY noted that the average grade of copper mined worldwide has declined by about 40% since 1991.
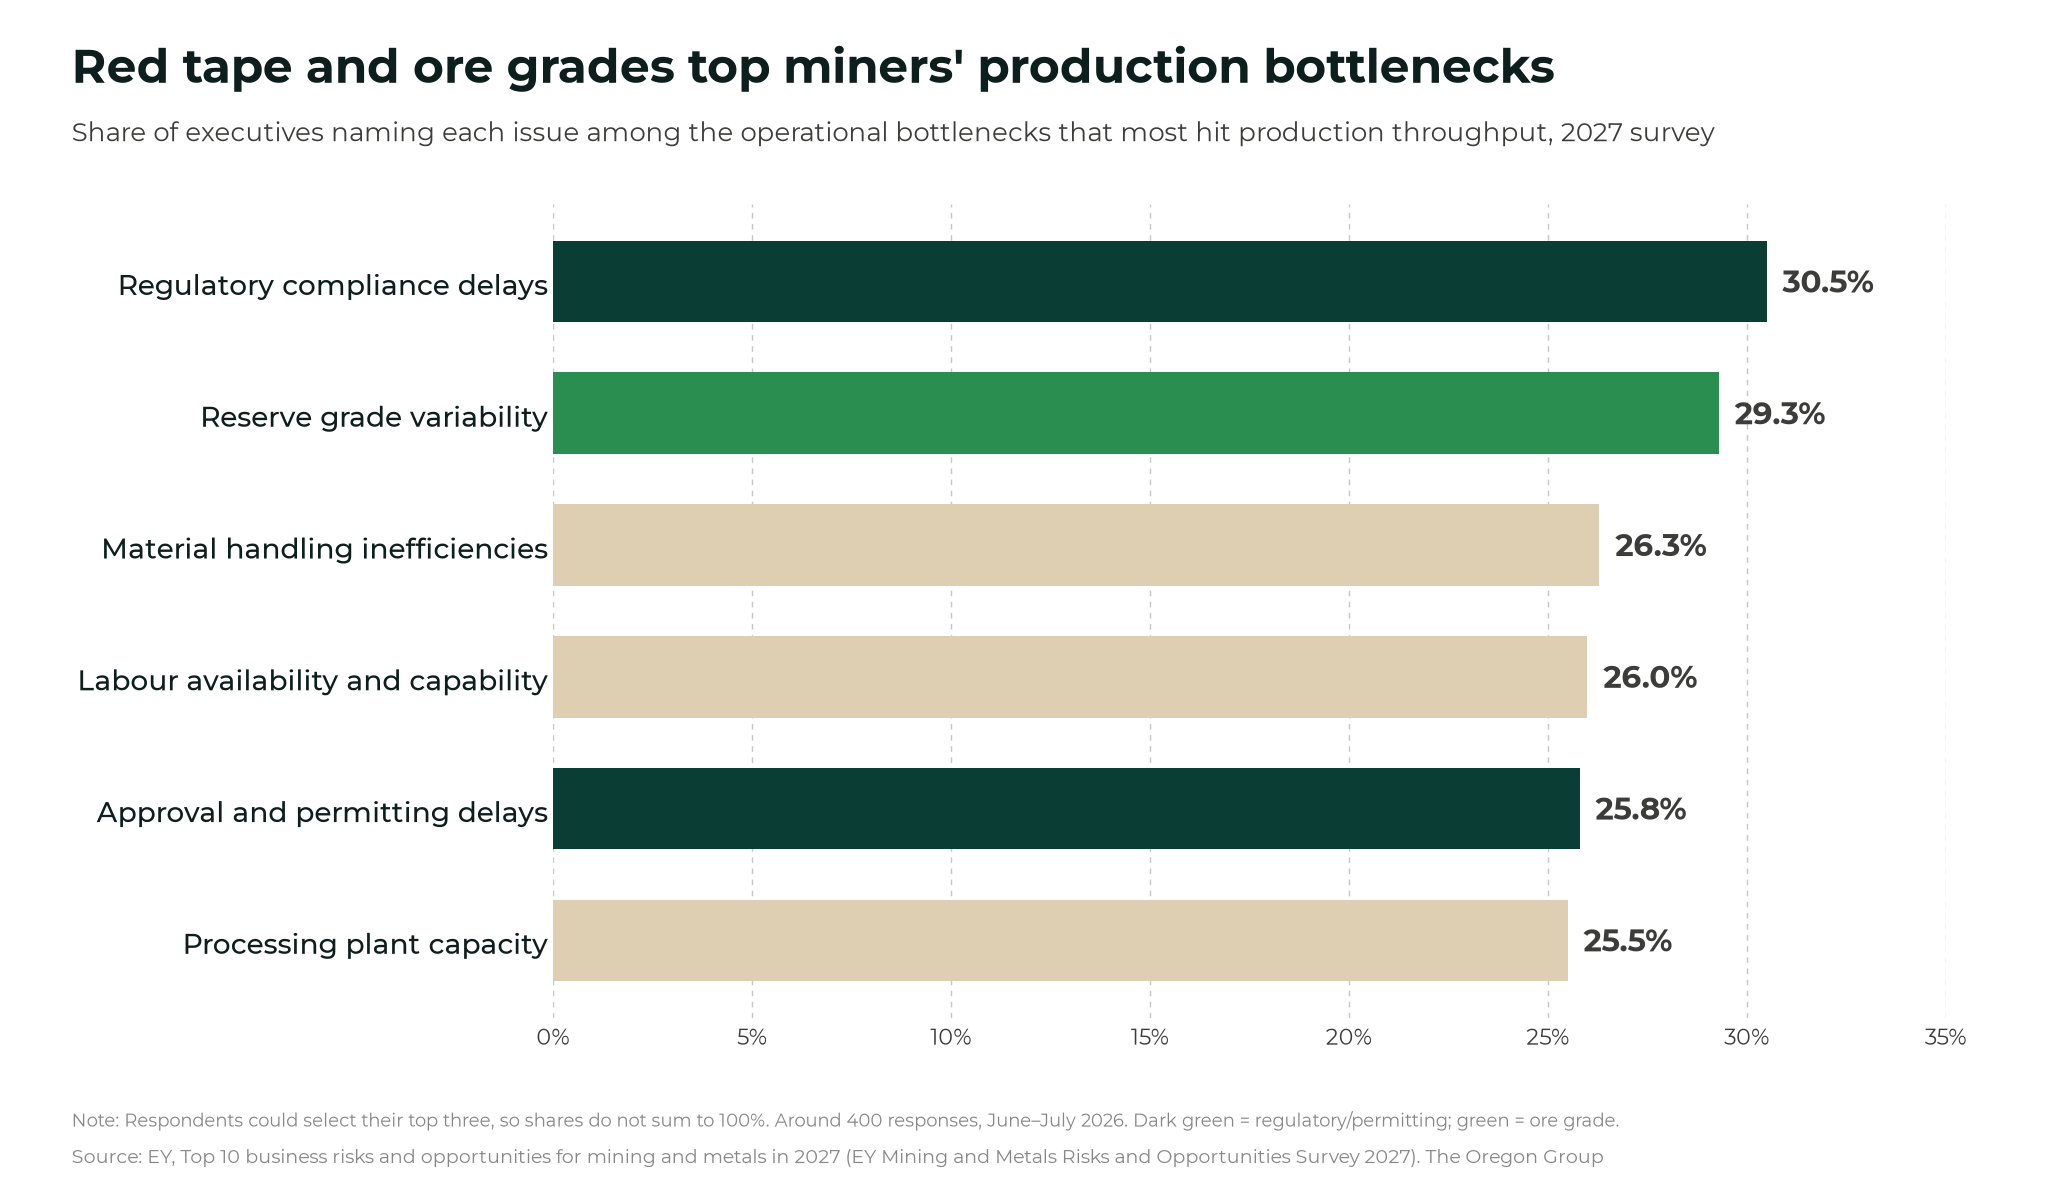
Bar chart of the operational bottlenecks EY's 2027 survey respondents said most affect production throughput, led by regulatory compliance delays at 30.5% and reserve grade variability at 29.3%

Chile shows the risk in practice

One of the most high-profile examples is Chile produced 3.63 million tonnes of copper in the first nine months of 2026, down 8.5% from a year earlier, according to Cochilco’s third-quarter copper market report, published on October 30. The state copper agency now expects full-year output of 4.94 million tonnes, down 8.4% on 2025. Its fourth-quarter 2025 report had expected 5.61 million tonnes.

Cochilco blames lower grades, maintenance, interruptions and ore variability — the same problems EY’s respondents ranked near the top.

Escondida, Codelco and Spence explain 77.3% of the national decline; for example:

  • Escondida produced 891,000 tonnes in January–September, down 12.5%. Its concentrator feed grade fell to 0.81% in the September quarter from 0.94% a year earlier, BHP said
  • Spence’s output fell 25.7%. BHP cited a lower feed grade of 0.53%, from 0.65%, and “ongoing challenges in managing ore variability”
  • Codelco’s own output fell 9.0%. Cochilco linked restrictions at El Teniente, down 17.1%, to the 2025 accident, and a 32.4% fall at Ministro Hales to lower grades


Supply chains and cybersecurity enter the top 10

But it’s not just operational challenges:

  • capital rose to No. 2 from No. 3.
  • supply chain enters the list at No. 3
  • geopolitics climbed to No. 5 from No. 7
  • the carbon agenda at No. 6
  • and cybersecurity at No. 9.

Notably, resource and reserve depletion, No. 4 last year, dropped out of the top 10. So did workforce and digital and innovation. That does not mean depletion stopped mattering. “Depletion can reduce operators’ choices,” EY said, leaving less flexibility to manage disruption.
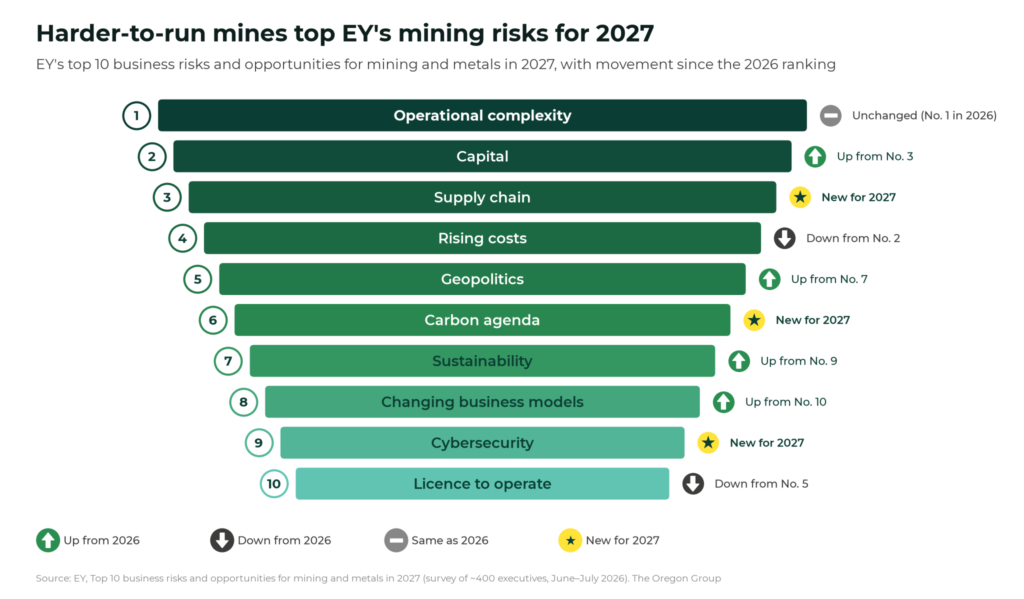
harder to run mines top EYs mining risks 2027 - The Oregon Group

Also, regards financing, EY says public financing for critical minerals more than quadrupled between 2023-2025 to about US$65 billion.

The caveats

EY’s ranking measures executive perception, not output, and it’s sample also fell to around 400 responses from 500 in last year’s survey.
Subscribe for Investment Insights. Stay Ahead.

Investment market and industry insights delivered to you in real-time.

Disclaimer

The Oregon Group maintains full editorial control over all content published on this website. While sponsored and advertised placements may be featured, the content remains the sole opinion of The Oregon Group. The author may receive compensation or remuneration for providing content, but all statements and expressions are made independently and are not influenced by sponsors or advertisers. From time to time, The Oregon Group and its directors, officers, partners, employees, authors, or members of their families, as well as persons who are interviewed for articles on this website, may have a long or short position in securities or commodities mentioned and may make purchases and/or sales of those securities or commodities in the open market or otherwise. By accessing and using this website, readers are cautioned to assume that each of the foregoing persons may have a financial interest in all companies and sectors mentioned on this website. Any projections, market outlooks or estimates herein are forward looking statements and are inherently unreliable., and any such statements are based upon certain assumptions and should not be construed to be indicative of the actual events that will occur.  Other events that were not taken into account may occur and may significantly affect the returns or performance of the securities or commodities discussed herein. The information provided herein is based on matters as they exist as of the date of preparation and not as of any future date, and The Oregon Group undertakes no obligation to correct, update or revise the information in this document or to otherwise provide any additional material. The information provided on this website is for informational purposes only and is not, directly or indirectly, an offer, solicitation of an offer and/or a recommendation to buy or sell any security or commodity, and the information provided on this website should not be construed as any advice or an opinion as to the price at which the securities of any company or commodity may trade at any time. The Oregon Group is a publisher of financial information, not an investment advisor.  We do not provide personalized or individualized investment advice or information that is tailored to the needs of any particular recipient, and the information provided on this website is not and should not be construed as personal, financial, investment or professional advice. Readers are cautioned to always do their own research and review of publicly available information and to consult their professional and registered advisors before purchasing or selling any securities or commodities and should not rely on the information contained herein. Neither The Oregon Group nor any of its affiliates accepts any liability whatsoever for any direct or consequential loss howsoever arising, directly or indirectly, from any use of the information contained herein. By using the Site or any affiliated social media account, you are indicating your consent and agreement to this disclaimer and our terms of use. Unauthorized reproduction of this newsletter or its contents by photocopy, facsimile or any other means is illegal and punishable by law.

Share this article

about the author

Picture of The Oregon Group

The Oregon Group

The Oregon Group is an investment research team focused on critical minerals, mining, energy and geopolitics.

Tags

Subscribe Now

Subscribe for in-depth market and industry intelligence you won’t find in the headlines.

Recommended to Read NEXT

GET FREE INVESTMENT INSIGHTS

Investment intelligence and in-depth reports on critical minerals, mining, energy and geopolitics — from capital-markets professionals with boardroom and institutional experience.