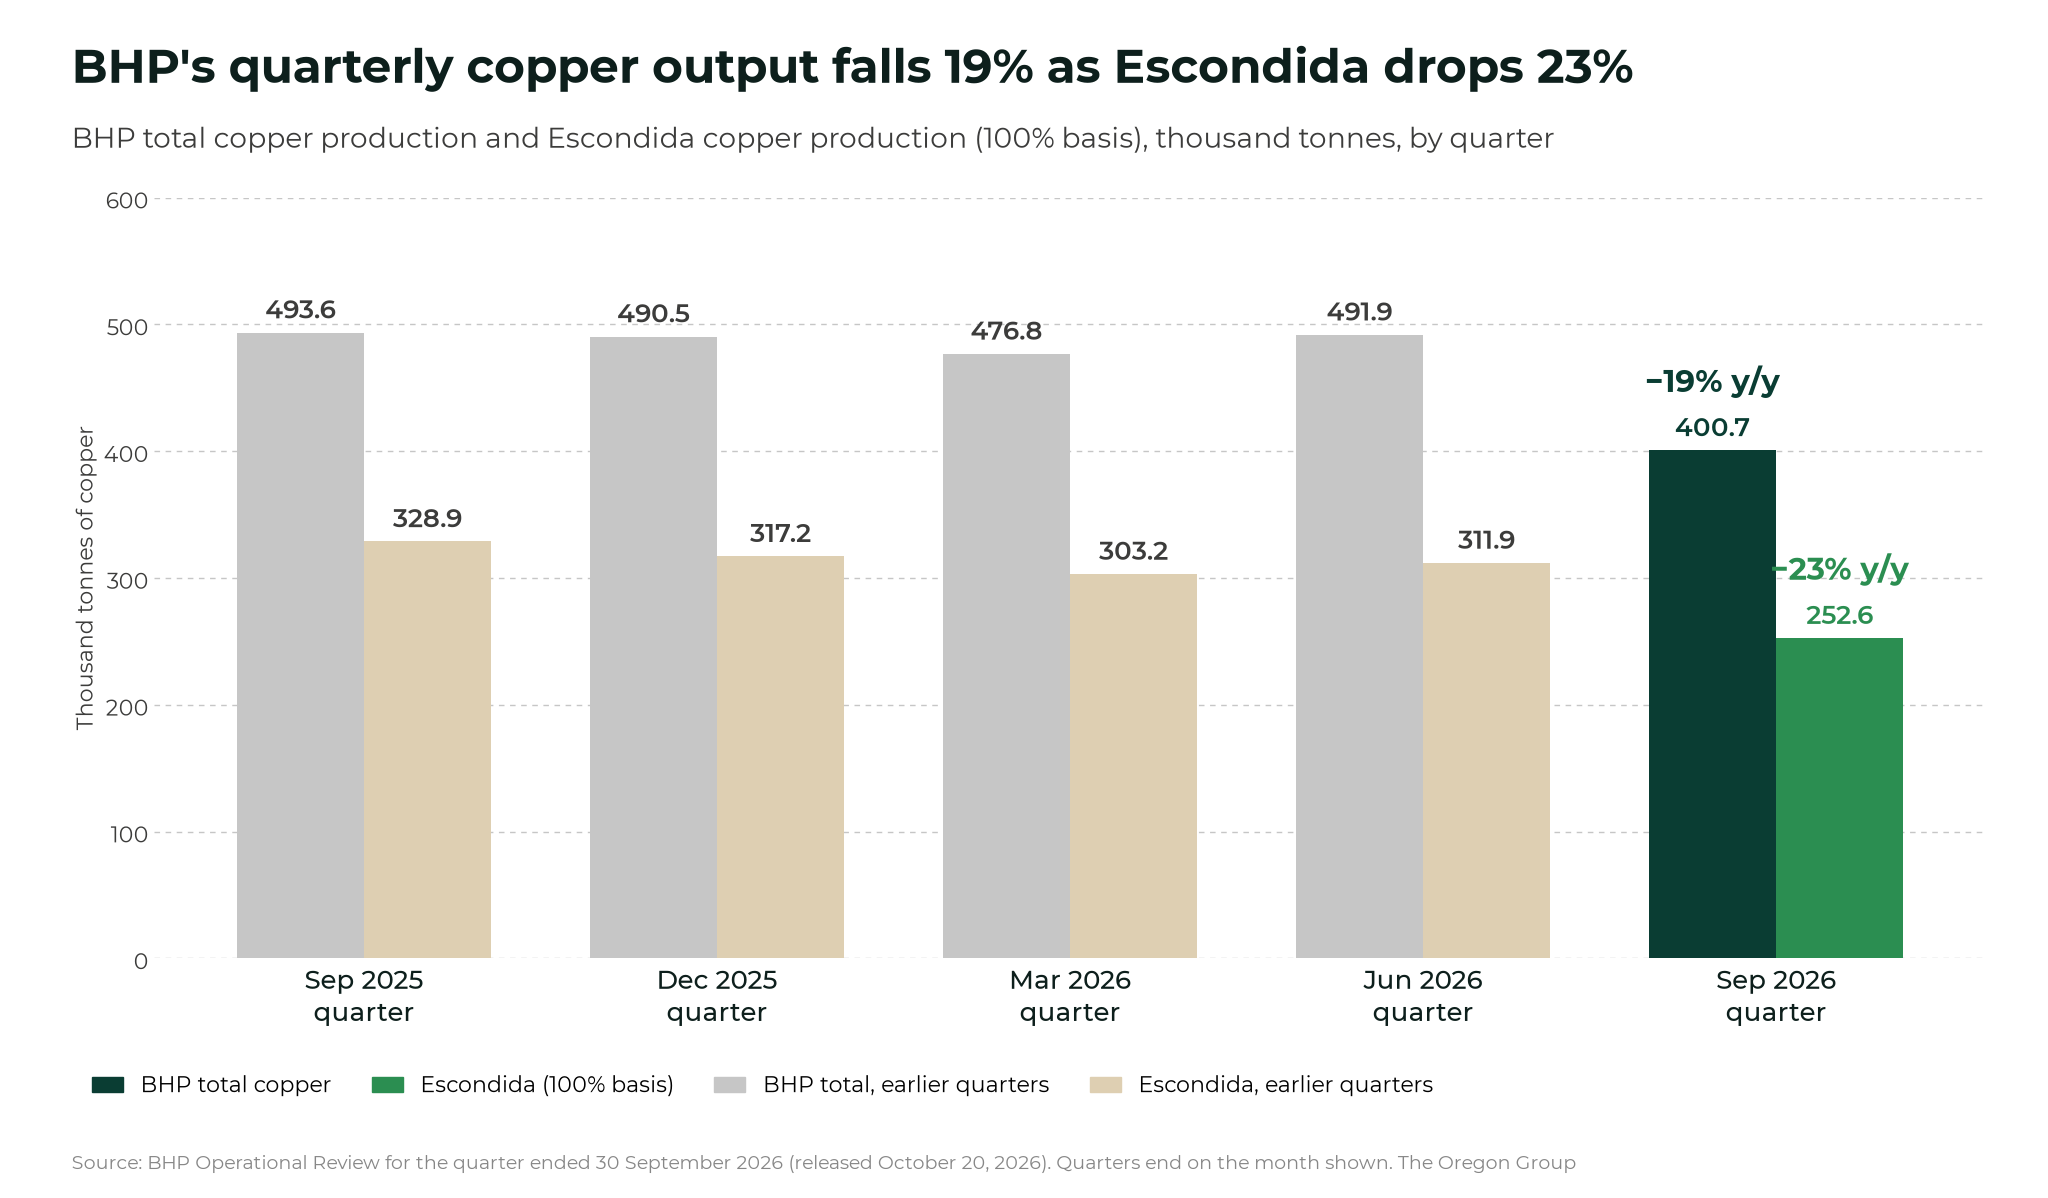
- BHP said on October 20 that its copper production fell 19% to 400,700 tonnes in the September quarter from a year earlier, with Escondida down 23%, but kept full-year guidance unchanged
- Anglo American’s copper output fell 5% to 174,900 tonnes in the third quarter after record snowfall in Chile, also with 2026 guidance unchanged
- both miners blamed mostly planned lower grades and temporary disruptions, but Chile’s mined copper output fell to 369,500 tonnes in August, its lowest month since February 2011
BHP’s copper production fell 19% to 400,700 metric tonnes in the three months to September 30, compared with a year earlier, as lower grades, maintenance and severe weather in Chile hit its biggest mine.
BHP kept its copper guidance for the year to June 2027 unchanged at 1.65–1.8 million tonnes.
Anglo American reported a 5% fall in copper output the same day, also blaming Chile’s winter weather.
Escondida led the fall
BHP’s Escondida mine in Chile produced 252,600 tonnes of copper on a 100% basis, down 23% from a year earlier. BHP owns 57.5% of the mine. Concentrator throughput at the mine also fell 14% from a year earlier.
BHP gave several reasons, including:
- a planned drop in concentrator feed grade to 0.81% copper, from 0.94% a year earlier, plus scheduled maintenance
- severe weather in July and August that constrained logistics and use of the truck fleet
- a temporary suspension of all mining after a fatal incident on September 23
Elsewhere, output at Spence fell 15% on lower grades, and Copper South Australia fell 16% after an underground conveyor belt failed at Carrapateena.
BHP chief executive Brandon Craig said most of the drop was planned or temporary.
“Copper production was lower in the first quarter, reflecting planned grade declines and scheduled maintenance, alongside temporary disruptions from severe weather in Chile, stops for safety and the conveyor failure at Carrapateena,” Brandon Craig said.
Anglo blames record snowfall in Chile
Anglo American’s Chilean copper output fell 6% to 94,200 tonnes, reflecting extreme winter weather and planned lower grades at Collahuasi and El Soldado.
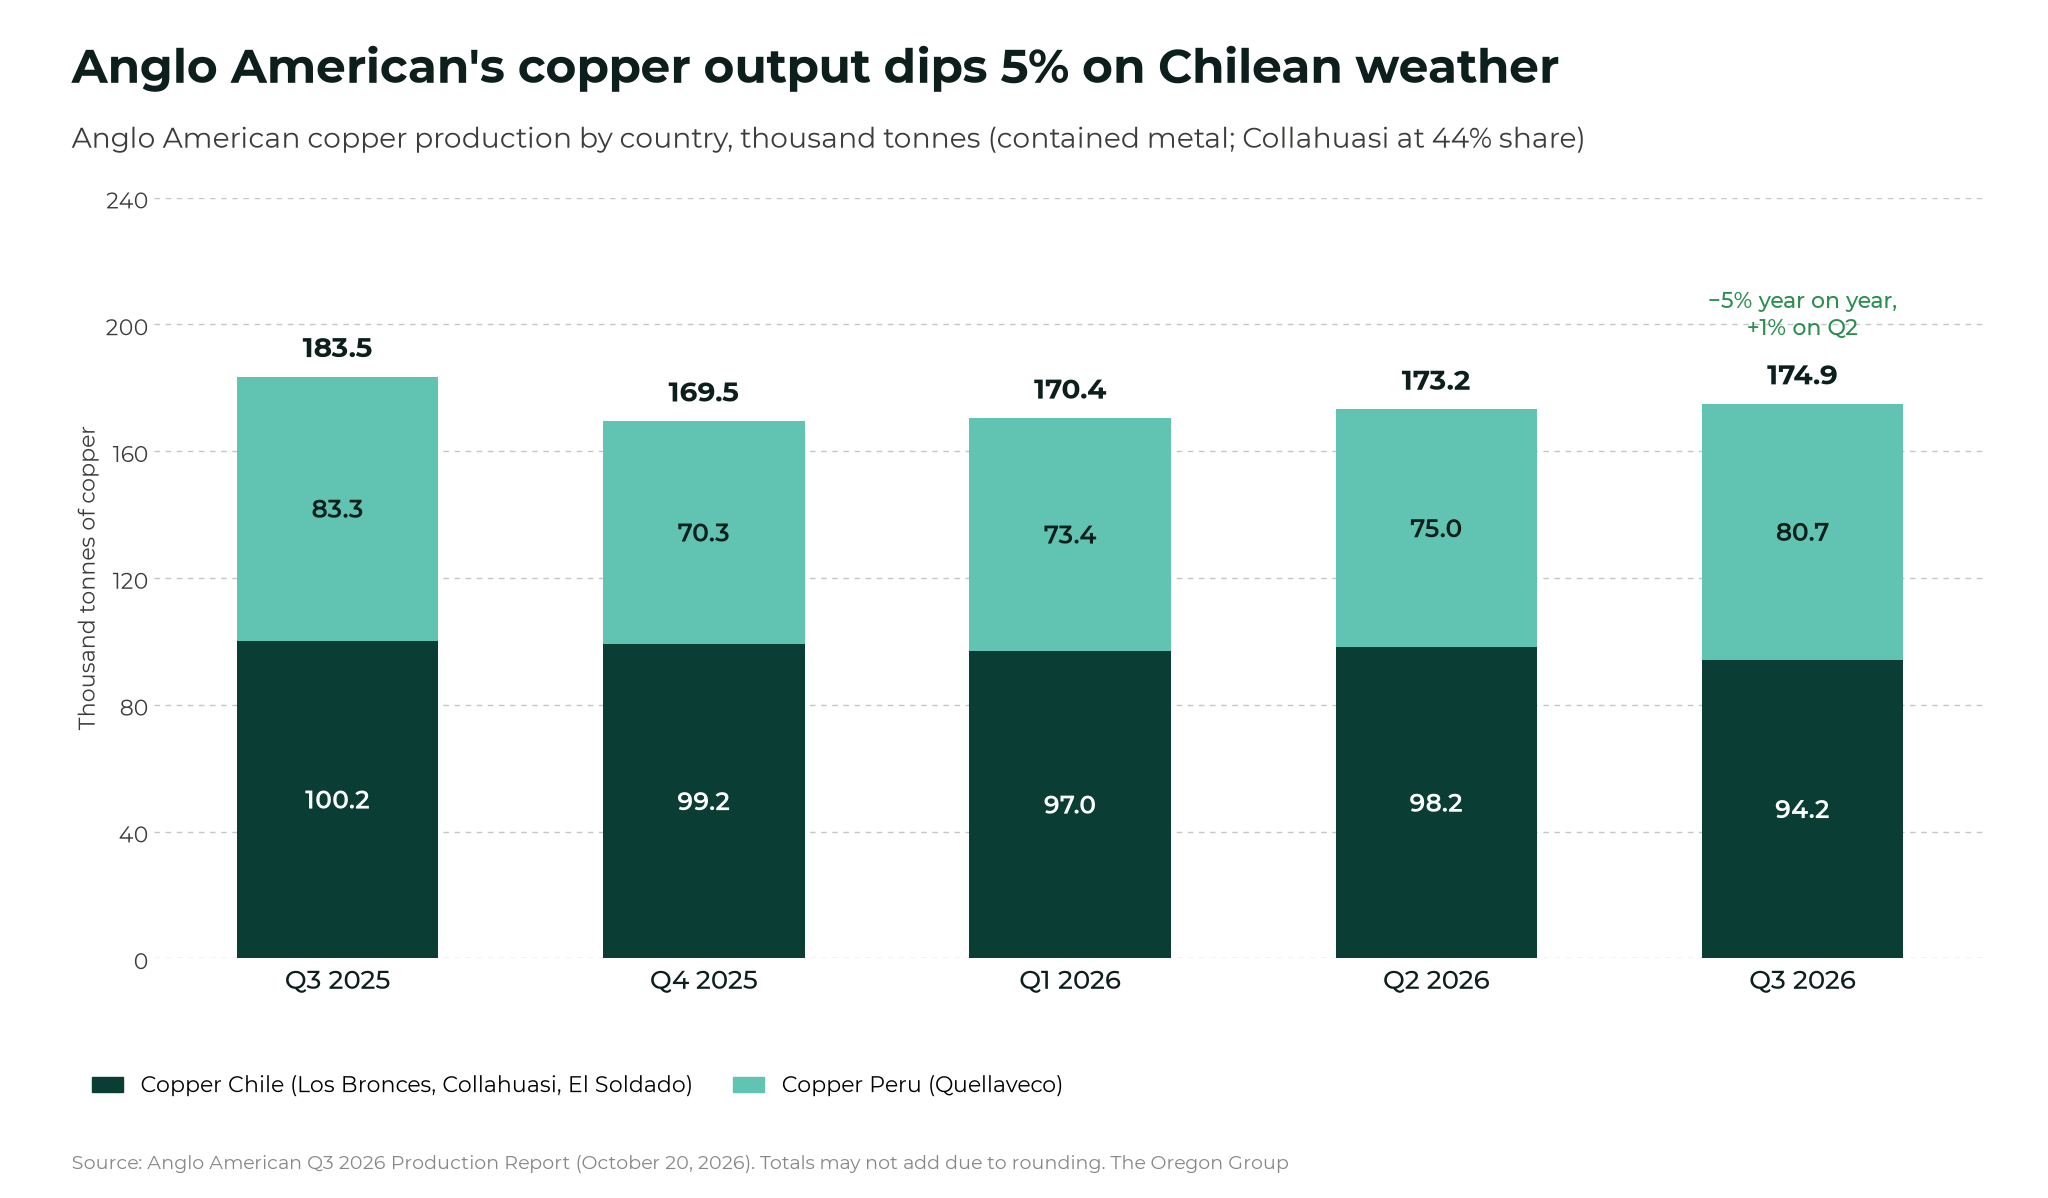
Its share of Collahuasi fell 11% to 42,000 tonnes. Severe weather in the Tarapacá region has carried on into the fourth quarter, and the mine was processing lower-grade stockpile ore; Los Bronces produced 2% more than a year earlier. However, throughput and mining rates there were more than 10% lower than in the second quarter after record snowfall; in Peru, Quellaveco’s output fell 3% to 80,700 tonnes on lower ore grades, though it rose 8% from the second quarter.
Anglo chief executive Duncan Wanblad said the company expects grades to improve.
“We are on track to meet our 2026 guidance, supported by the planned improvement in copper ore grades in the fourth quarter,” Duncan Wanblad said.
Anglo kept its 2026 copper guidance at 700,000–760,000 tonnes, with Chile and Peru both weighted to the second half.
Chile’s supply problem is broader than two miners
Chile produced 369,500 tonnes of mined copper in August, according to the national statistics institute (INE). That was the lowest monthly total since February 2011, according to La Tercera, citing Cochilco data.
Andrés González, head of mining at consultancy Plusmining, told La Tercera the weakness goes beyond the weather.
“Twelve of the last 13 months have recorded year-on-year falls in copper production. This reinforces the thesis that, beyond the effects of the storm or other one-off factors, national mining is going through a structural cycle of lower production,” Andrés González said.
As we noted in our earlier article Refined copper surplus forecast, but copper mines struggle to keep up:
“And primary copper mine supply continues to see declining ore grades and disruption.”
There were some offsets, for example:
- Antofagasta’s third-quarter output rose 7% from the second quarter to 151,900 tonnes, and it kept its 2026 guidance
- the Centinela strike ended on October 18 after unions and Minera Centinela reached a 36-month agreement
- BHP’s share of copper from Antamina, in Peru, rose 18% to 40,000 tonnes on planned higher grades
Prices are doing the heavy lifting
For the companies, higher prices are cushioning the volume loss, with Brandon Craig saying stronger prices are a tailwind for earnings, “particularly in copper”.
BHP’s average realised copper price rose 53% to US$7.01 a pound from a year earlier.
And the market’s tightness is structural, with the International Copper Study Group forecasting a refined copper surplus of about 104,000 tonnes in 2026, widening to 368,000 tonnes in 2027.
BHP itself describes the copper market as “broadly balanced” for now, while saying demand is expected to exceed committed supply in the coming years. In other words, weaker mine output in Chile has not yet tipped the refined market into deficit.