- US defence suppliers say a new non-Chinese mine or refinery for critical minerals such as tungsten, germanium and rare earths for magnets can take up to 10 years to build and certify, and significant US magnet and processing capacity is not expected until 2028 or later
- the costs are already rising, with some defence suppliers reporting source-transition costs above US$10 million and one stockpiling material at more than 30 times historic prices
- Washington has lined up US$27.3 billion for minerals projects, but the industry wants waivers of about two years for magnets, tungsten and germanium when the ban starts on January 1, 2027
In less than 60 days, the Pentagon will stop buying rare-earth magnets, tungsten and tantalum that were mined, refined or processed in China — but the industry that has to comply says a new mine or refining source to replace that supply can take up to 10 years to identify, build and certify.
The timeline comes from Strengthening Critical Minerals Supply Chains, a report published by the Aerospace Industries Association (AIA), representing nearly 300 companies employing more than 2 million US workers.
The nearer-term picture is not much better, with the AIA warning significant US processing, refining and magnet capacity for aerospace-grade material is not expected “until 2028 or later”, and qualification then typically adds another 12–24 months before the material can enter defence production.
One member company said many domestic supply projects are not due online until 2029 or 2030.
“Ultimately sources of domestic supply are unlikely to match demand for at least the next decade.”
— AIA member company
As far back (!) as 2023, we wrote in US Military and Critical Minerals: The New Arms Race that:
“None of this is possible without critical minerals to build it and power it.”
— The Oregon Group
Since then, money has flowed into mines and plants, but the bottleneck has moved further down the chain, into processing, purity and qualification, and those can take years to fix.
What breaks first?
Few in industry expect fully compliant supply by January 1, 2027, so the possible repercussions range quite widely, but below are some of the outcomes to watch out for:
- the deadline bends before the supply chain does: S&P Global reported on October 16 that the magnet ban is likely to require waivers, which Executive Order 14415 still allows for contractors with accepted mitigation plans; the House’s Section 1803 would go further, phasing in upstream sourcing to 2031 with renewable two-year waivers, though it is a proposal, not law.
But if “China-free” becomes a goal rather than a rule, the policy premium for compliant material could fade, which is the key risk for investors. - a two-price market for heavy rare earths: dysprosium oxide in Europe has traded at about 4.9 times China’s domestic price, and terbium oxide at 3.8 times, with Benchmark Mineral Intelligence forecasting in March that the dysprosium gap in North America would widen from 4.4 times in 2025 to 8.3 times by 2027. The split is not universal: ex-China NdPr oxide fell to US$95,000 a tonne in August, below the US$110/kg floor in MP Materials’ and Lynas’s Pentagon deals
- China holds the clock: Beijing put export controls on heavy rare earths, including dysprosium and terbium, on April 4, 2025, and Chinese customs data show no dysprosium or terbium oxide shipped to Japan in 2026. Its wider trade truce with Washington, which keeps broader controls on hold, now runs to January 10, 2027, China’s Commerce Ministry said on September 28, which is nine days after the Pentagon ban starts
- money moves to refining, not mines: the National Defense Industrial Association (NDIA) said in a July 2026 white paper that Pentagon efforts “have focused heavily on extraction rather than on refining.” If the bottleneck stays in processing, the next round of capital is likely to favour separation, refining and magnet plants over new mines
- allies become the bridge: the US–Australia framework of October 2025 set a US$8.5 billion project pipeline, and a year on it has more than A$6 billion in conditional financing across more than 12 projects. A US–Japan framework followed on October 28, 2025, and on June 17, 2026 the G7 aimed to cut reliance on any single outside supplier of rare earths and magnets to under 60% by 2030. But even that target allows heavy reliance on one supplier well beyond January 2027
- defence output and costs take the hit: without enough waivers, the AIA warns, programmes “could face production disruptions, cost increases, and schedule delays,” and members are already studying part redesigns that need lengthy requalification. There is a precedent when the Pentagon halted F-35 deliveries on August 31, 2022 after Honeywell disclosed that lube-pump magnets in the jet’s turbomachine used Chinese samarium-cobalt alloys, and resumed them only under a waiver covering 126 aircraft
From mine to finished part takes four years or more
The AIA’s timelines explain why the January deadline is so hard to meet: even with a compliant mine of qualified material, the report says the path from extraction to a finished item delivered to the Department of War “can span four years or more.”
In other words, parts delivered in 2027 rest on sourcing decisions made years ago, when alternatives outside China and the other covered countries were not available.
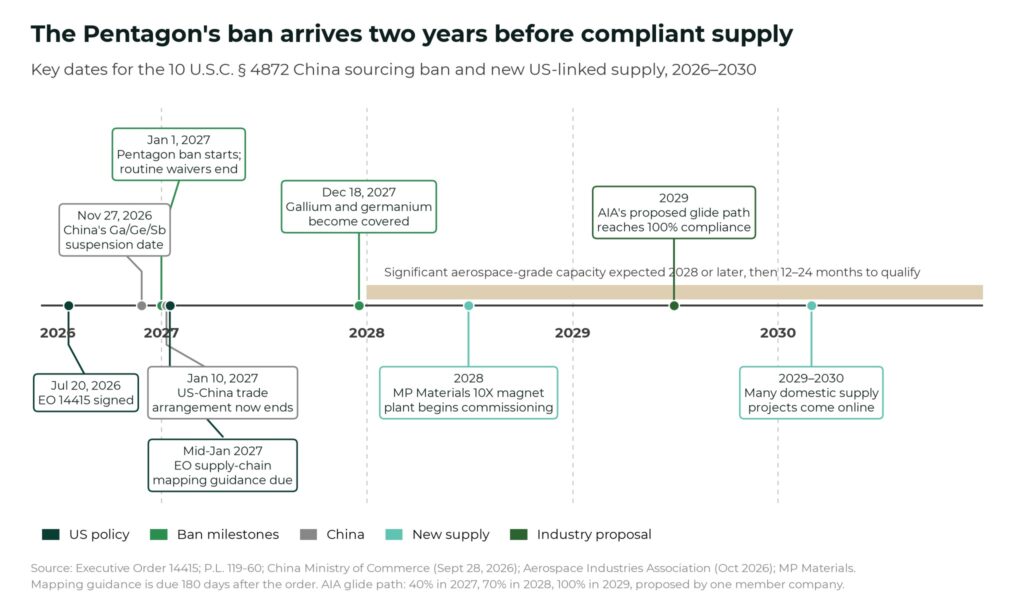
That is why AIA members want waivers of about two years for samarium-cobalt and neodymium-iron-boron (NdFeB) magnets, germanium and tungsten. One company also proposed a glide path, with 40% compliance in 2027, 70% in 2028 and 100% by 2029.
As one AIA member company put it:
“Until compliant neodymium-iron-boron magnets and germanium become commercially available in the required specifications, purity, and volumes, [our company] cannot begin the qualification and testing process.”
— AIA member company
We made the same point in July, in US suppliers not ready for Pentagon’s 2027 ban on China-sourced magnets and minerals:
“This is why the deadline is so difficult: the bottleneck is not the ore body, but the supply and processing chain between the mine and the finished magnet.”
— The Oregon Group
Independent figures support the AIA’s timelines; for example, in 2025, US demand for the most common type of rare-earth magnet was roughly 48,000 metric tonnes, while domestic sources supplied 300 tonnes.
US firms are on track to have capacity for 5,000 tonnes by the end of 2026, but other gaps go back decades — for example, US firms have not produced tungsten since 2015, or tantalum since 1959.
New mines and refineries are coming, but on the industry’s timeline of years, not the Pentagon’s deadline of weeks. For example:
- MP Materials: the magnet facility it is building for the Pentagon is slated to open in 2028
- Energy Fuels: plans to process 6,000 metric tonnes of rare earths a year by 2029
- Vulcan Elements: its North Carolina magnet plant is slated to open by 2030
The Army now says the same thing, with Liz Miranda, Army Materiel Command’s executive deputy to the commanding general, telling the Association of the US Army (AUSA) conference on October 14, Breaking Defense reported, that mapping its supply chains “is no easy task.”
“We’re working towards that. Are we there yet? No. So we are going to see some impact come January.”
— Liz Miranda, Army Materiel Command
The cost of switching is already rising
The AIA does not put a total price on securing the supply chain, but its survey shows where the costs are landing.
Some companies reported source-transition costs above US$10 million. One member secured supply through 2029 and beyond by stockpiling material “at prices exceeding 30 times historic market rates.”
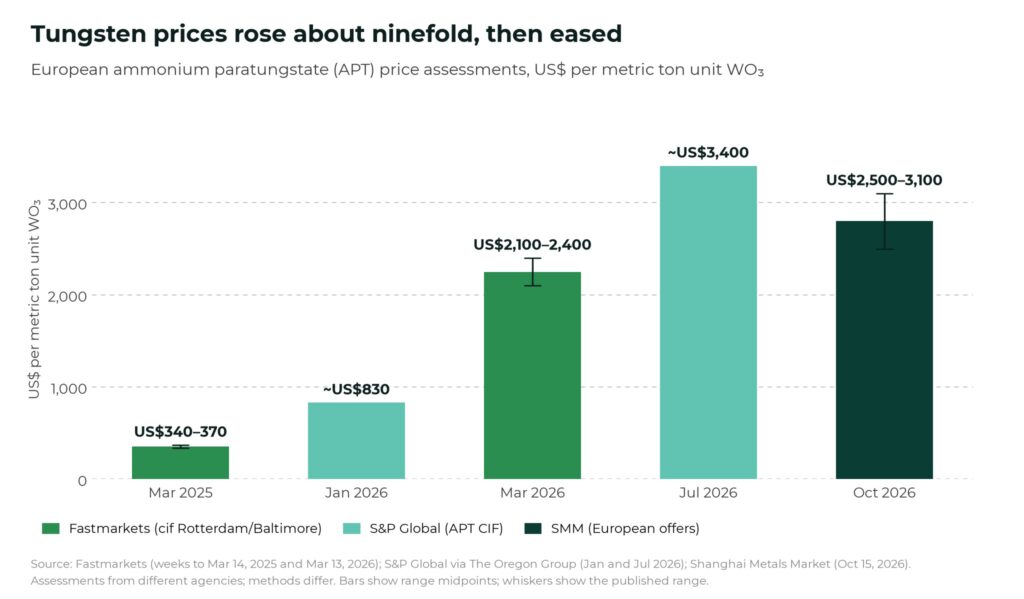
Prices for the raw material have jumped too. Rotterdam tungsten prices roughly doubled in 2025, the AIA says, from US$266 to US$551 per metric ton unit for concentrate and from US$331 to US$675 for ammonium paratungstate (APT). Then the rise sped up. Fastmarkets assessed Rotterdam APT at US$2,100–2,400 per metric ton unit in mid-March 2026, and APT reached about US$3,400 in July 2026. It has since eased with European APT offers falling to US$2,500–3,100 per metric ton unit in mid-October.
Germanium is tighter still. Fastmarkets’ July average for Rotterdam germanium metal was US$10,000–12,750/kg, against US$1,289–1,400/kg in June 2023, the month before China announced export controls.
Heavy rare earths are now moving on the deadline itself. Fastmarkets’ terbium oxide price rose 41% to US$5,000–8,000/kg in the week to October 1, from US$4,200–5,000/kg on September 24; dysprosium oxide rose to US$2,500–3,500/kg, from US$1,910–2,500/kg.
Market participants say US consumers are willing to pay significantly more than buyers in Europe ahead of the January restrictions.
The volumes are small, but hard to fill.
Sprott estimates the Pentagon needs about 3,000–4,000 metric tonnes a year of specialised rare-earth magnets, rising to about 10,000 tonnes by 2030. That compares with global magnet demand of about 250,000 tonnes a year and ex-China output of only 20,000–25,000 tonnes.
In AIA and PwC’s July 2026 survey, 77% of respondents named specialty metals among their top three inflation drivers.
Meanwhile, the suppliers at the bottom of the chain are the least able to pay.
Raw materials providers reported no capacity to scale beyond twice current volumes on any predictable timeline, and 43% reported capital gaps, while reporting no use of federal industrial base capital vehicles.
In August, we warned in Tungsten price shock signals deeper supply crisis that the Pentagon’s 2027 deadline:
“increasingly divides the market between material that meets US procurement rules and material that does not”
— The Oregon Group
Washington is paying to close the gap
The US government has not been standing still.
As we reported in America’s $27 billion push to break China’s minerals grip, the Payne Institute counts US$27.3 billion across 62 projects, although about 65% of it is conditional.
For rare earths alone, the Center for Strategic and International Studies (CSIS) counts more than US$7.3 billion committed by five US government departments and agencies, in an April 27 brief — but it warned:
“Unless significantly more capacity comes online in the next eight months, adhering to this requirement may not be feasible.”
— Gracelin Baskaran and Meredith Schwartz, CSIS
The Department of War’s own deals now reach from mine to magnet; for example:
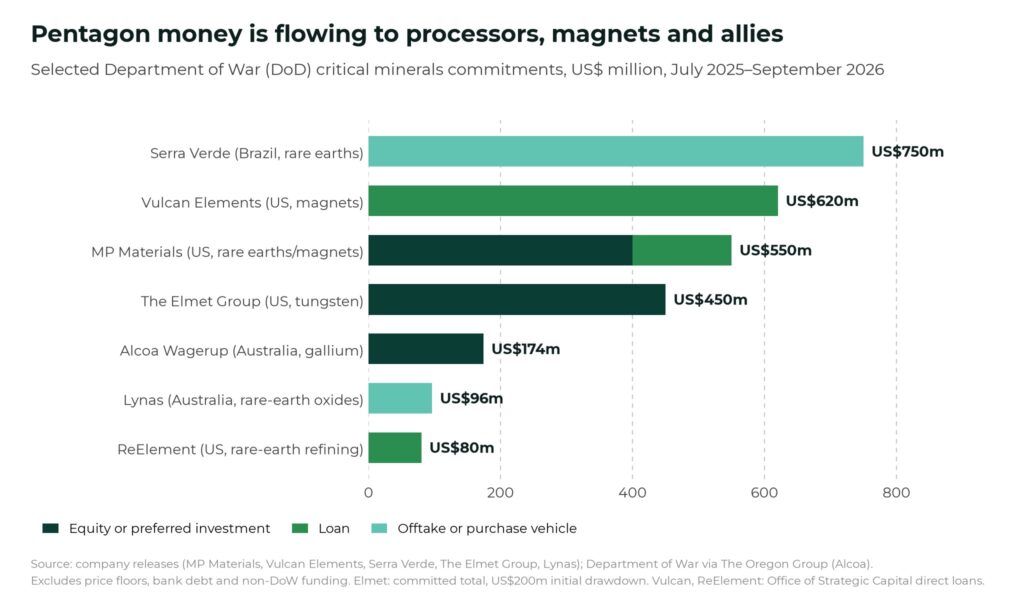
- MP Materials: a US$400 million preferred equity investment, a US$150 million loan, a US$110/kg NdPr price floor for 10 years and a 10-year offtake for its 10X magnet plant, which is due to begin commissioning in 2028
- Serra Verde: a US$750 million investment in a vehicle buying Brazilian rare-earth carbonate under a 15-year offtake, with floors of US$575/kg for dysprosium and US$2,050/kg for terbium
- The Elmet Group: a US$450 million committed investment in September, including about US$150 million for an APT plant in Nevada
- Vulcan Elements: a US$620 million Office of Strategic Capital direct loan for a 10,000-tonne magnet plant, plus US$80 million for partner ReElement
- gallium: about US$174 million for Alcoa’s Wagerup plant in Western Australia, which is expected to produce 100 tonnes a year, about 10% of global demand
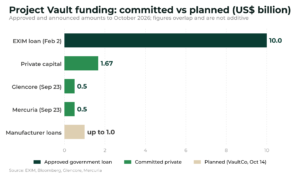
Separately, Project Vault, the Export-Import Bank’s US$12 billion reserve, has taken its first copper delivery and is lining up US$1 billion in loans.
But AIA members are concerned that Project Vault will, in fact, compete with them for the same scarce material.
And not every plan survives contact with reality — Lynas switched about US$96 million of Pentagon funding from a planned heavy rare-earth plant in Texas to a four-year oxide offtake, because of “significant uncertainty” over whether the plant would be built.
Back in April, in US invests $8.6 billion in critical minerals deals since January 2025, we said:
“For mining companies the scale of the investment by the US government helps put a floor in the risk involved in moving ahead with projects.”
— The Oregon Group
That floor is real, but a floor price does not make a magnet. Most of these plants will be commissioning in 2028 or later, and then their output has to be qualified.
What the ban covers, and when
The rule is 10 U.S.C. § 4872. From January 1, 2027, it bars the Department of War from buying covered materials that were mined, refined, separated, processed or produced in China, Russia, Iran or North Korea, as well as applying to products that contain those materials.
Covered materials include, for example:
- samarium-cobalt and NdFeB magnets
- tungsten metal powder and heavy alloys
- tantalum metals and alloys
- molybdenum, gallium and germanium
The timing differs by material, so, for example, under the FY2026 National Defense Authorization Act, gallium and germanium only become covered materials on December 18, 2027, two years after the act became law. Molybdenum was added with no delay.
Executive Order 14415, signed on July 20, 2026, tightened the rule further. After January 1, routine waivers end unless a contractor has an accepted mitigation plan that documents “exhaustive” efforts to find compliant material.
AIA chief executive Eric Fanning told Breaking Defense in July that the executive order is:
“an unrealistically tight time frame without a lot of exceptions allowed.”
— Eric Fanning, AIA
Congress is already rewriting the deadline
Congress may yet change the rules.
The House version of the FY2027 defence bill, H.R. 8800, includes Section 1803, which would rewrite 10 U.S.C. § 4872 around two tiers of materials. This is a House proposal, not law, but if enacted, the new rules would take effect 180 days after the bill becomes law — so, until then, the January 1 deadline stands.
- Tier 1 covers finished and refined materials such as magnets, tungsten heavy alloy, NdPr and tantalum; these would stay barred from the covered countries, with at least 50% of their cost from domestically owned producers
- Tier 2 covers upstream inputs such as tungsten ores, concentrates and APT, rare-earth oxides and intermediates, and niobium. Here, the minimum share sourced outside the covered countries would phase in, for example:
- 25% in 2028
- 50% in 2029
- 75% in 2030
- 100% from January 1, 2031
Waivers would last up to two years, renewable, but each would need a transition plan with “quantifiable milestones.” An analysis by SAFE’s Center for Critical Minerals Strategy put the tension plainly:
“Congress can move a comma faster than industry can permit, finance, build, qualify, and scale key parts of magnet supply chains.”
— Abigail Hunter and Zubeyde Oysul, SAFE
Notably, the House timetable for upstream material is slower than the glide path one AIA member proposed, which reached 100% by 2029.
Material by material, the gaps are in processing
The AIA’s most important finding is simple. For several covered materials, compliant aerospace-grade material “is not commercially available today from domestic or allied sources.”
And the problem is mostly not ore. Instead, the main constraint, the report says, is processing, refining and manufacturing capacity for aerospace-grade material, “rather than access to the raw material itself.”
The gaps vary by material; for example:
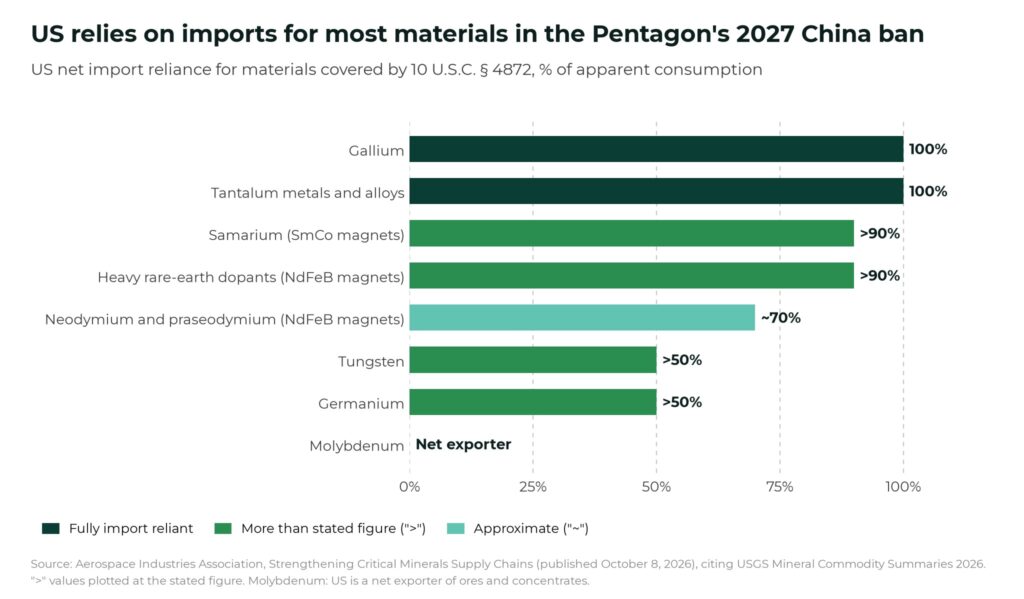
- NdFeB and samarium-cobalt magnets: US net import reliance is about 70% for neodymium and praseodymium and more than 90% for heavy rare-earth dopants and samarium. One member said suppliers lack the facilities “to produce DFARS-compliant magnets until 2028”
- tungsten: China accounts for about 80% of mine output and 85% of APT production. Aerospace is a small buyer in a market with “a large structural supply gap”
- germanium: US net import reliance is above 50%, and one member warned that “compliant domestic sourcing at the required purity and volume is limited”
- tantalum and molybdenum: tantalum is 100% import-reliant, with China supplying 47% of refined metal and powder imports. The US is a net exporter of molybdenum ore, but China controls exports of the refined powders that defence uses
Purity is the “hidden” challenge, with one company warning no refiner, allied or domestic, had yet met its specifications for some rare earths, including any applications requiring 99.99% purity.
NDIA’s July white paper also noted that the Pentagon accounted for less than 0.1% of global rare-earth purchases, according to a 2024 GAO report.
Gallium and germanium are further behind, as an October 2025 letter to the armed services committees, NDIA warned:
“Creating a supply ecosystem for germanium and gallium is anticipated to require significantly more time than the 36-month waiver process allows.”
— National Defense Industrial Association
China still holds the switch
Beijing, of course, knows the calendar too. In November 2025, China suspended its ban on gallium, germanium and antimony exports to the US, but the metals still need export licences. As we wrote in China lifts export ban gallium, germanium, antimony:
“investors and policymakers should view the move as a reprieve, not a resolution”
— The Oregon Group
That suspension was set to run until November 27, 2026, before the broader Kuala Lumpur trade arrangement was extended to January 10, 2027.
China’s ban on exports to US military users remains in place, and magnet flows are volatile: China’s rare-earth magnet exports to the US fell 21% in August to 512 tonnes.
Who benefits
For investors, the AIA report is a demand signal with a catch.
Defence demand for compliant material is real and growing, but it pays for qualified material at specification, not tonnes in the ground.
That favours a few groups, for example:
- allied producers already operating: Almonty’s Sangdong mine in South Korea received final operating certificates on September 17, with more than 90% of Phase I output contracted for 21 years
- processors and magnet makers with offtake: MP Materials, Vulcan Elements and Elmet have government buyers, and in some cases price floors
- recyclers: tantalum, tungsten and molybdenum made from recycled material have statutory exceptions, and recycling already supplies about 35% of global tungsten demand
- by-product producers: gallium and germanium mostly come from alumina and zinc processing, so existing refineries can move faster than new mines
The downside is just as clear: if China eases licences, or prices fall as they have in tungsten since July, the economics of higher-cost ex-China supply weaken.
The case against more delay
The AIA is an industry lobby asking for more time, so its request deserves scrutiny — and the deadline is not new — Congress set the January 2027 date in the 2021 defence authorization act, giving contractors six years to prepare.
Some suppliers want the deadline enforced. Nick Myers, chief executive of Phoenix Tailings, which received a US$500 million Pentagon loan in June, told Reuters:
“Defence contractors have just assumed they can keep buying Chinese products. The defense industry is never going to stop if you keep giving waivers.”
— Nick Myers, Phoenix Tailings
Some companies expect to comply for certain applications by January 1, the report says, and the 10-year figure is an upper bound that depends on the material.
Waivers already exist.
Under DFARS 225.7018-4, the Pentagon can issue class determinations. Michael Cadenazzi, the Pentagon’s assistant secretary for industrial base policy, told Breaking Defense on July 22 that “if there’s a gap, a legitimate gap, [and] you have a plan and you need a window to see you through [to] bridge that gap, that’s what we want to know.”
Peter Cook of the Breakthrough Institute told S&P Global:
“The defense contractor procurement date is not an industry-wide cliff because the rules allow exceptions if eligible materials are unavailable”
— Peter Cook, Breakthrough Institute
Another delay would also blunt the signal investors need.
SAFE’s Center for Critical Minerals Strategy warns that “repeated delays, new exceptions, or shifting requirements risk undermining confidence in the durability of demand and discouraging investment.” And even the glide path proposed in the AIA’s report, reaching 100% compliance by 2029, accepts that the deadline should bite.
As we wrote in The missile race is becoming a race for critical minerals:
“Before America can reload its missile stockpiles, it must first reload its critical-mineral supply chains”
— The Oregon Group
The ban starts on January 1 — on the AIA’s own timelines, compliant supply is at least two years behind it, and possibly a decade.