- MPs say they cannot be confident the Government passes any of 10 tests for reducing reliance on China
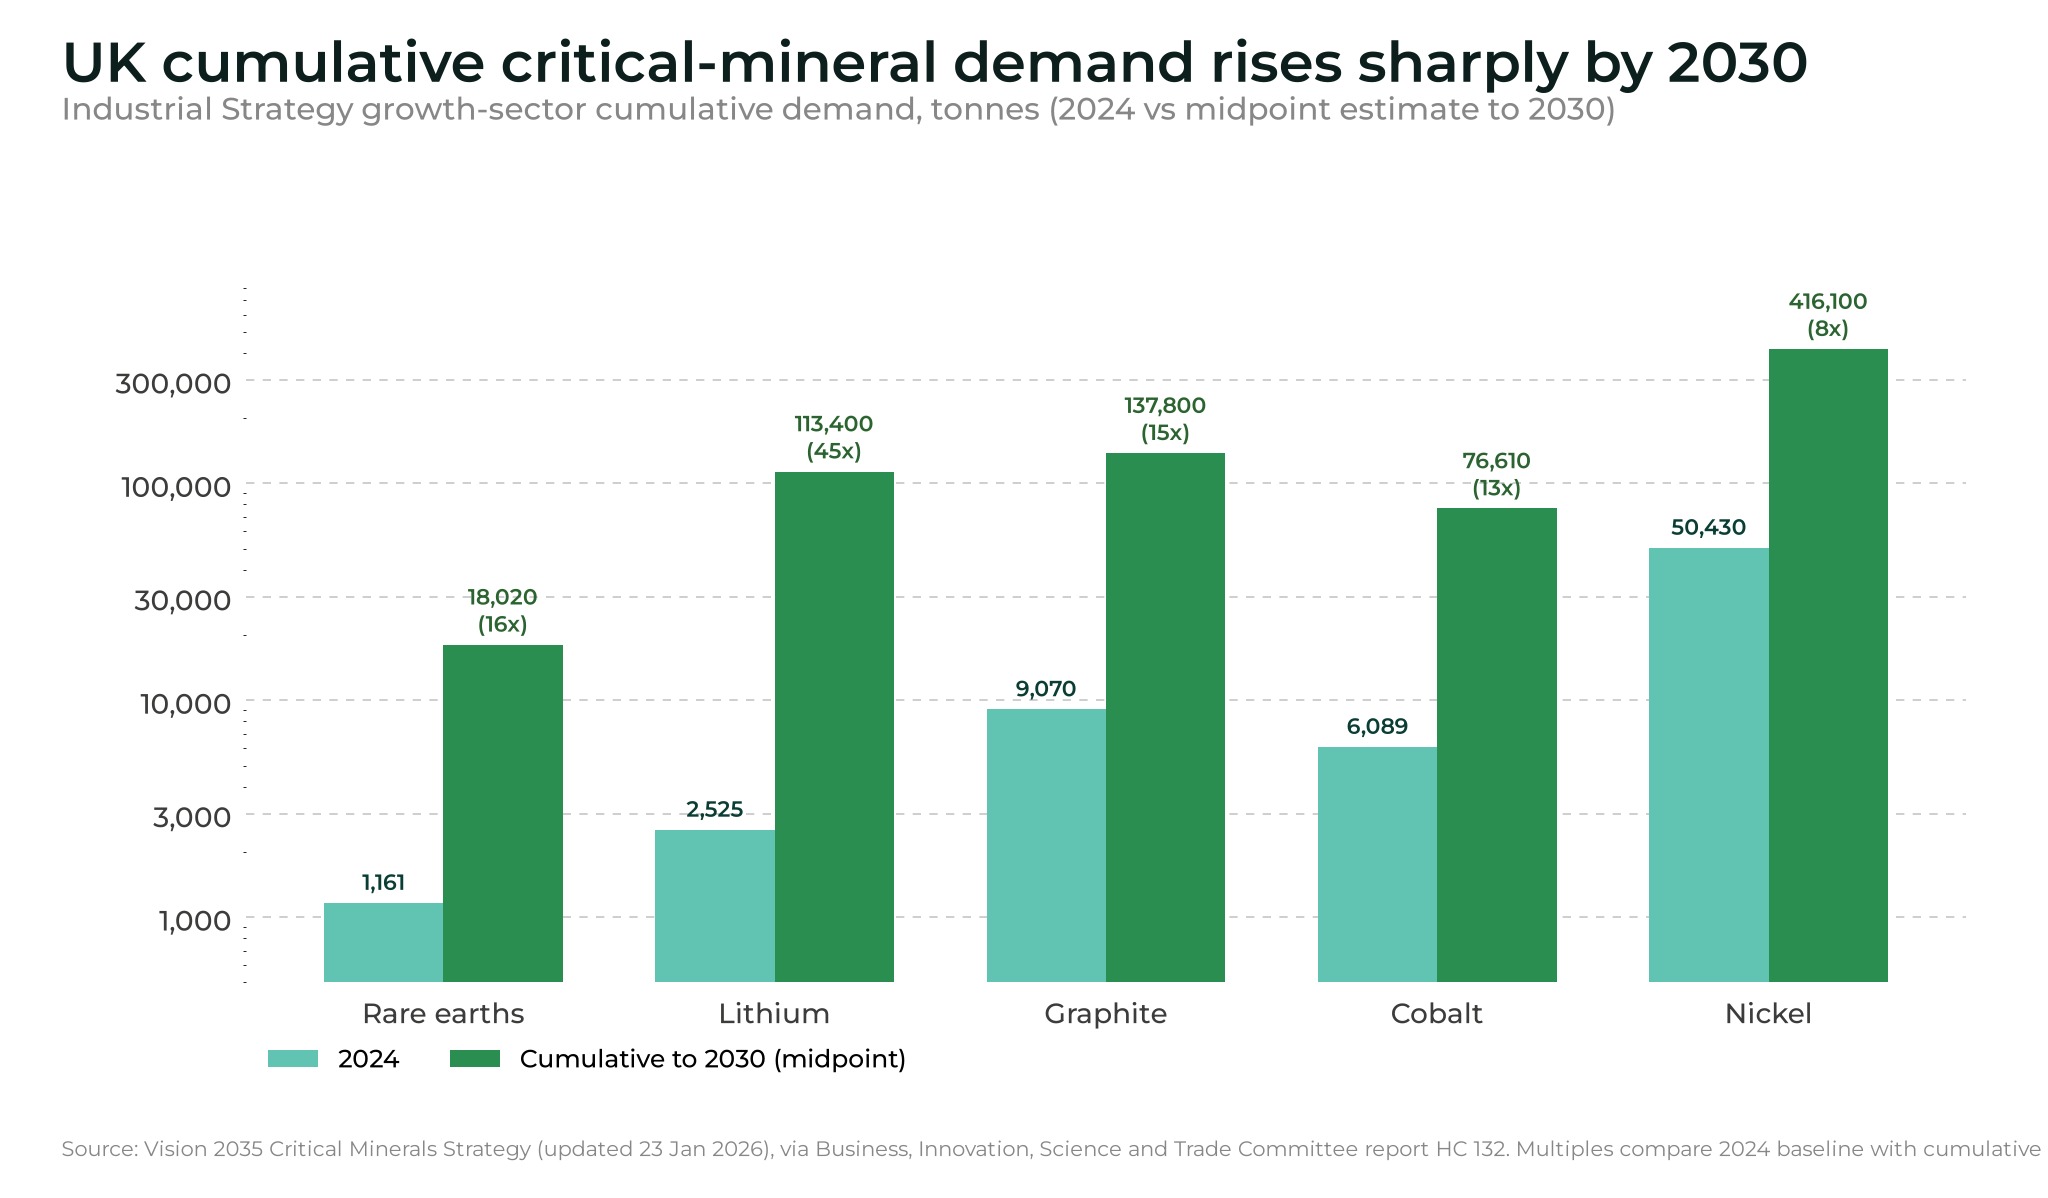
- cumulative UK demand for rare earths across Industrial Strategy growth sectors is projected to reach 18,020 tonnes by 2030, up from 1,161 tonnes in 2024, according to government figures cited by a House of Commons committee
- UK lithium demand in the same cumulative series rises from 2,525 tonnes in 2024 to 113,400 tonnes by 2030, with graphite, cobalt and nickel also sharply higher
MPs say they cannot be confident that the UK government passes any of ten tests for cutting dangerous dependence on China for critical minerals, in a House of Commons report — which also shows cumulative rare-earth demand for Industrial Strategy growth sectors rising from 1,161 tonnes in 2024 to 18,020 tonnes by 2030.
The Business, Innovation, Science and Trade Committee published its Critical minerals report (HC 132) on 5 November 2026.
The report warns Britain cannot re-arm, deliver net zero or build artificial intelligence infrastructure without securing the minerals those technologies need. Permanent magnets made from rare earths sit in wind turbines, electric-vehicle motors, data centres and defence platforms.
Demand is rising while refining stays concentrated
The committee uses the government’s own estimates of how much of each mineral Britain’s priority industries, such as clean energy, defence and advanced manufacturing, will need.
On those figures, the UK’s cumulative demand from 2024 to 2030 compares with 2024 alone as follows:
- rare earths: 18,020 tonnes, up from 1,161 tonnes (x15)
- lithium: 113,400 tonnes, up from 2,525 tonnes (x45)
- graphite: 137,800 tonnes, up from 9,070 tonnes (x15)
- cobalt: 76,610 tonnes, up from 6,089 tonnes (x13)
- nickel: 416,100 tonnes, up from 50,430 tonnes (x8)
The bottleneck is not only mining.
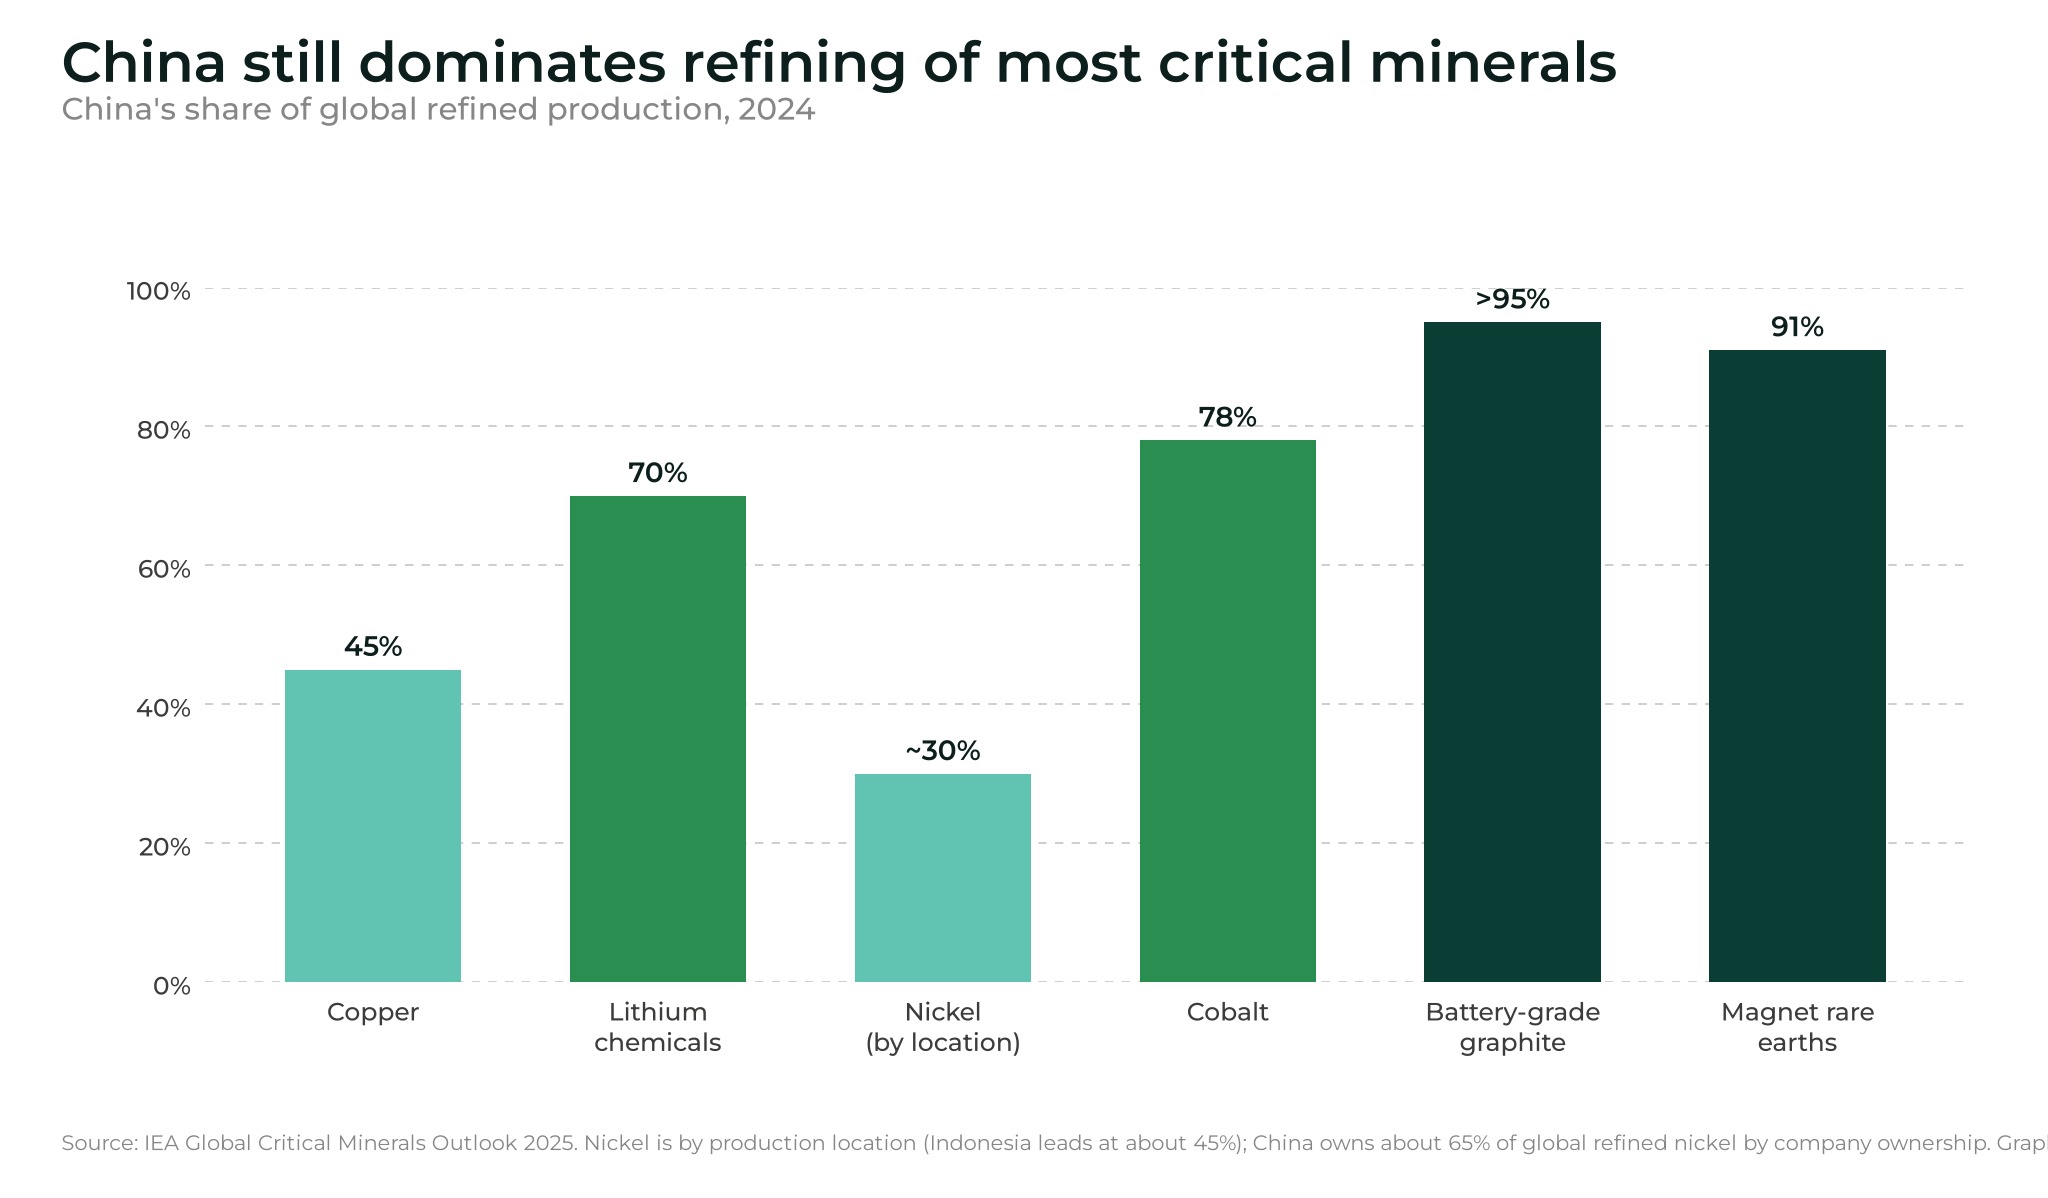
Dr Gavin Mudd, director of the UK Critical Minerals Intelligence Centre, told the inquiry that “the processing stage … is where the bottlenecks are” — the International Energy Agency estimates China is the leading refiner for 19 of 20 strategic minerals, with an average market share of about 70% — for magnet rare earths alone, China’s share of refining was about 91% in 2024.
China’s dominance matters for countries like the UK and US because China has already used export restrictions as a matter of geopolitical leverage: in April 2025 it imposed export controls on a group of rare earths after US tariffs, with shortages quickly spreading through car makers in the US and Europe. A later US-China deal suspended parts of the regime, but a licensing system remains, and James Kynge of Chatham House told MPs China still has a “chokehold” over rare-earth supply worldwide.
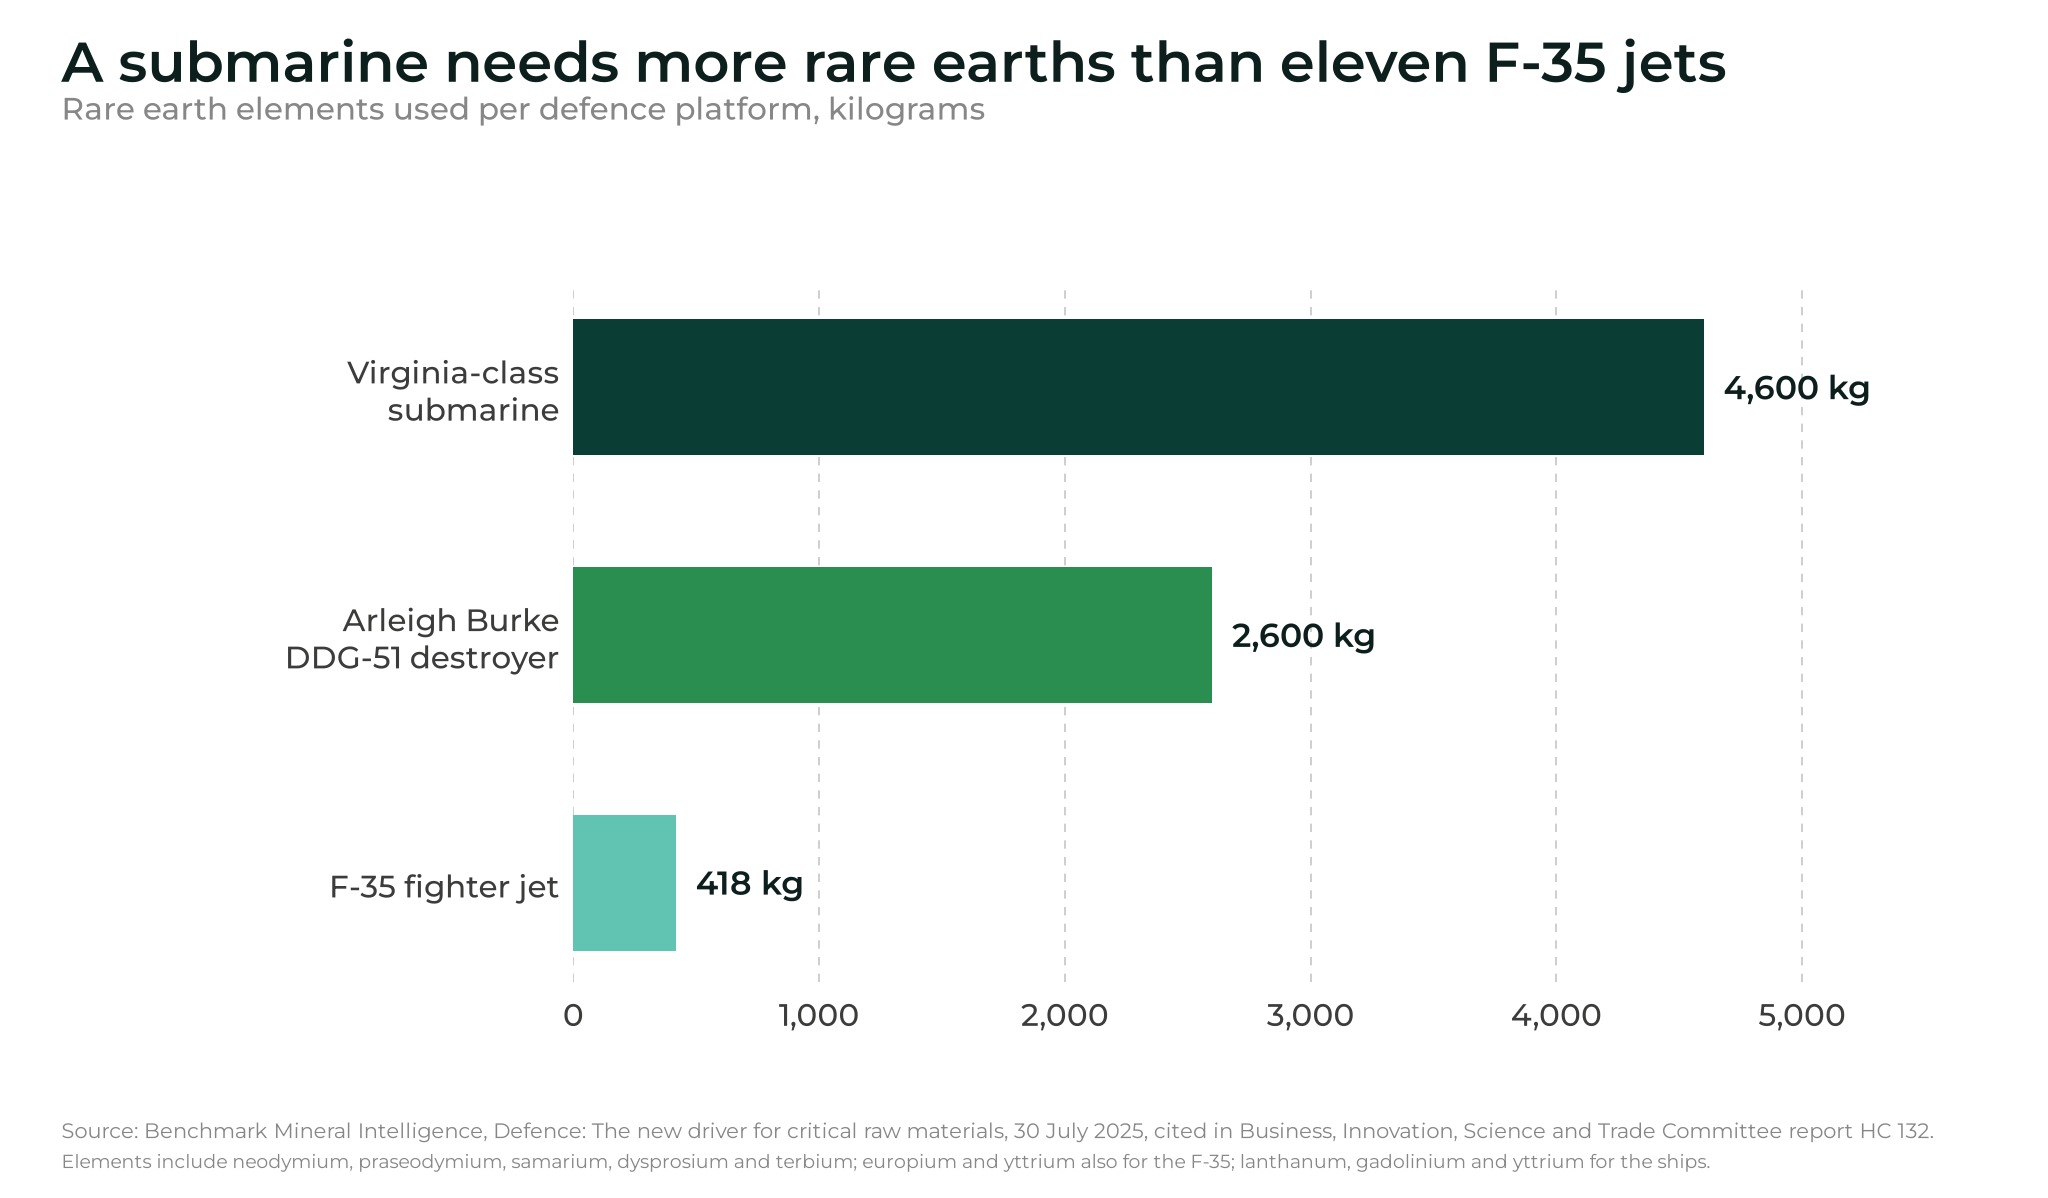
Rearmament makes both government concern and the volumes involved a matter of national security. for example, Benchmark Mineral Intelligence estimates an F-35 fighter jet uses about 418 kilograms of rare earths, an Arleigh Burke destroyer about 2,600 kilograms, and a Virginia-class submarine about 4,600 kilograms, figures the committee cites in its report.
We have covered the same midstream problem from the US and G7 side. The G7 has aimed to cut reliance on any single outside supplier of rare earths and permanent magnets to under 60% by 2030. The Pentagon is pouring capital into non-Chinese magnets and refining, including its stake in MP Materials. The UK report is the British version of that recognition: processing and magnets, not just mines, decide who is exposed.
Ten tests, and a failing grade
To hold ministers to account, the committee set ten tests. They cover what capabilities the UK wants to protect, how much mineral demand that implies, what allies need, where the chokepoints are, what can be mined or recycled at home, whether energy and planning rules support projects, whether skills are in place, whether allied offtake deals exist, whether the full financing stack is available, and whether companies are actually diversifying.
“Today, we cannot be confident that the Government passes any single one of these ten tests,” the report says.
Chair Liam Byrne put it more bluntly: “Critical minerals are the alpha of the new economy.” He said Britain remains “dangerously exposed” sixteen years after China first cut rare-earth exports to Japan in 2010.
The UK is almost completely import-dependent for critical minerals and has no domestic rare-earth mining or refining capacity, the report notes. About 80% of UK metal waste is exported rather than recycled at home. The National Wealth Fund’s US$33.5 million (£25 million, at US$1.34 to the pound on 6 November 2026) minimum equity ticket leaves many early-stage projects needing US$6.7 million to US$27 million (£5 million to £20 million) stranded.
Where the money and the opportunity sit
The committee’s answer is institutional muscle.
It recommends a Critical Minerals Finance Facility that can pull together UK Research and Innovation, British International Investment, UK Export Finance and the National Wealth Fund, then deploy grants, equity, debt, guarantees, offtakes and price floors. It also wants allied “buyers’ clubs” to share the cost of new mines and smelters, which can reach about US$3 billion apiece.
Some capital is already moving.
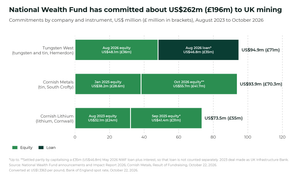
In August 2026 the National Wealth Fund announced up to US$95 million (£71 million) for Tungsten West to restart the Hemerdon tungsten mine in Devon, with an exclusive negotiation window over up to 50% of annual output, and in October the UK’s state-owned National Wealth Fund (NWF) is put US$55.7m (£41.7m) into Cornish Metals to support tin mining.
Vision 2035 targets 10% of UK critical-mineral demand from domestic production and 20% from recycling by 2035, with no more than 60% of aggregate demand from any one country.
The UK already has pieces of a non-Chinese magnet chain: Ionic Technologies is developing magnet recycling and refining in Belfast; Less Common Metals in Cheshire makes rare-earth metals and alloys and was acquired by USA Rare Earth; HyProMag, backed by Mkango, is building magnet recycling and manufacturing in Birmingham. Those plants are not named in the committee report, but they sit where MPs say Britain should put money: processing, recycling and magnets. That is also where UK policy still lags the US, which has used equity, loans, offtakes and price floors while London still leans on strategy papers and export-credit rules with a 20% UK-export test.
Complete decoupling from China is neither realistic nor desirable, the committee itself says, and Chinese refined rare-earth components remain five to six times cheaper than Western equivalents, but it appears the government has take notice.
Conclusion
We warned in 2024 that the UK’s critical mineral and energy supply, between revolution and disaster — it appears the government is now agreed and warning of the need to avert disaster.